- Attachment pdf 2 MB EV NDC World Map (Print Version)
-
Press Release
More than 120 countries aim to expand electric mobility
Agora Verkehrswende’s interactive world map shows countries’ ambitions for expanding electric mobility under the Paris Agreement
EV NDC World Map
Interactive map of global ambition to adopt electric vehicles (EVs) based on the Nationally Determined Contributions (NDCs) of Paris Agreement signatories
Data current to 30 September 2026
1. The EV NDC World Map
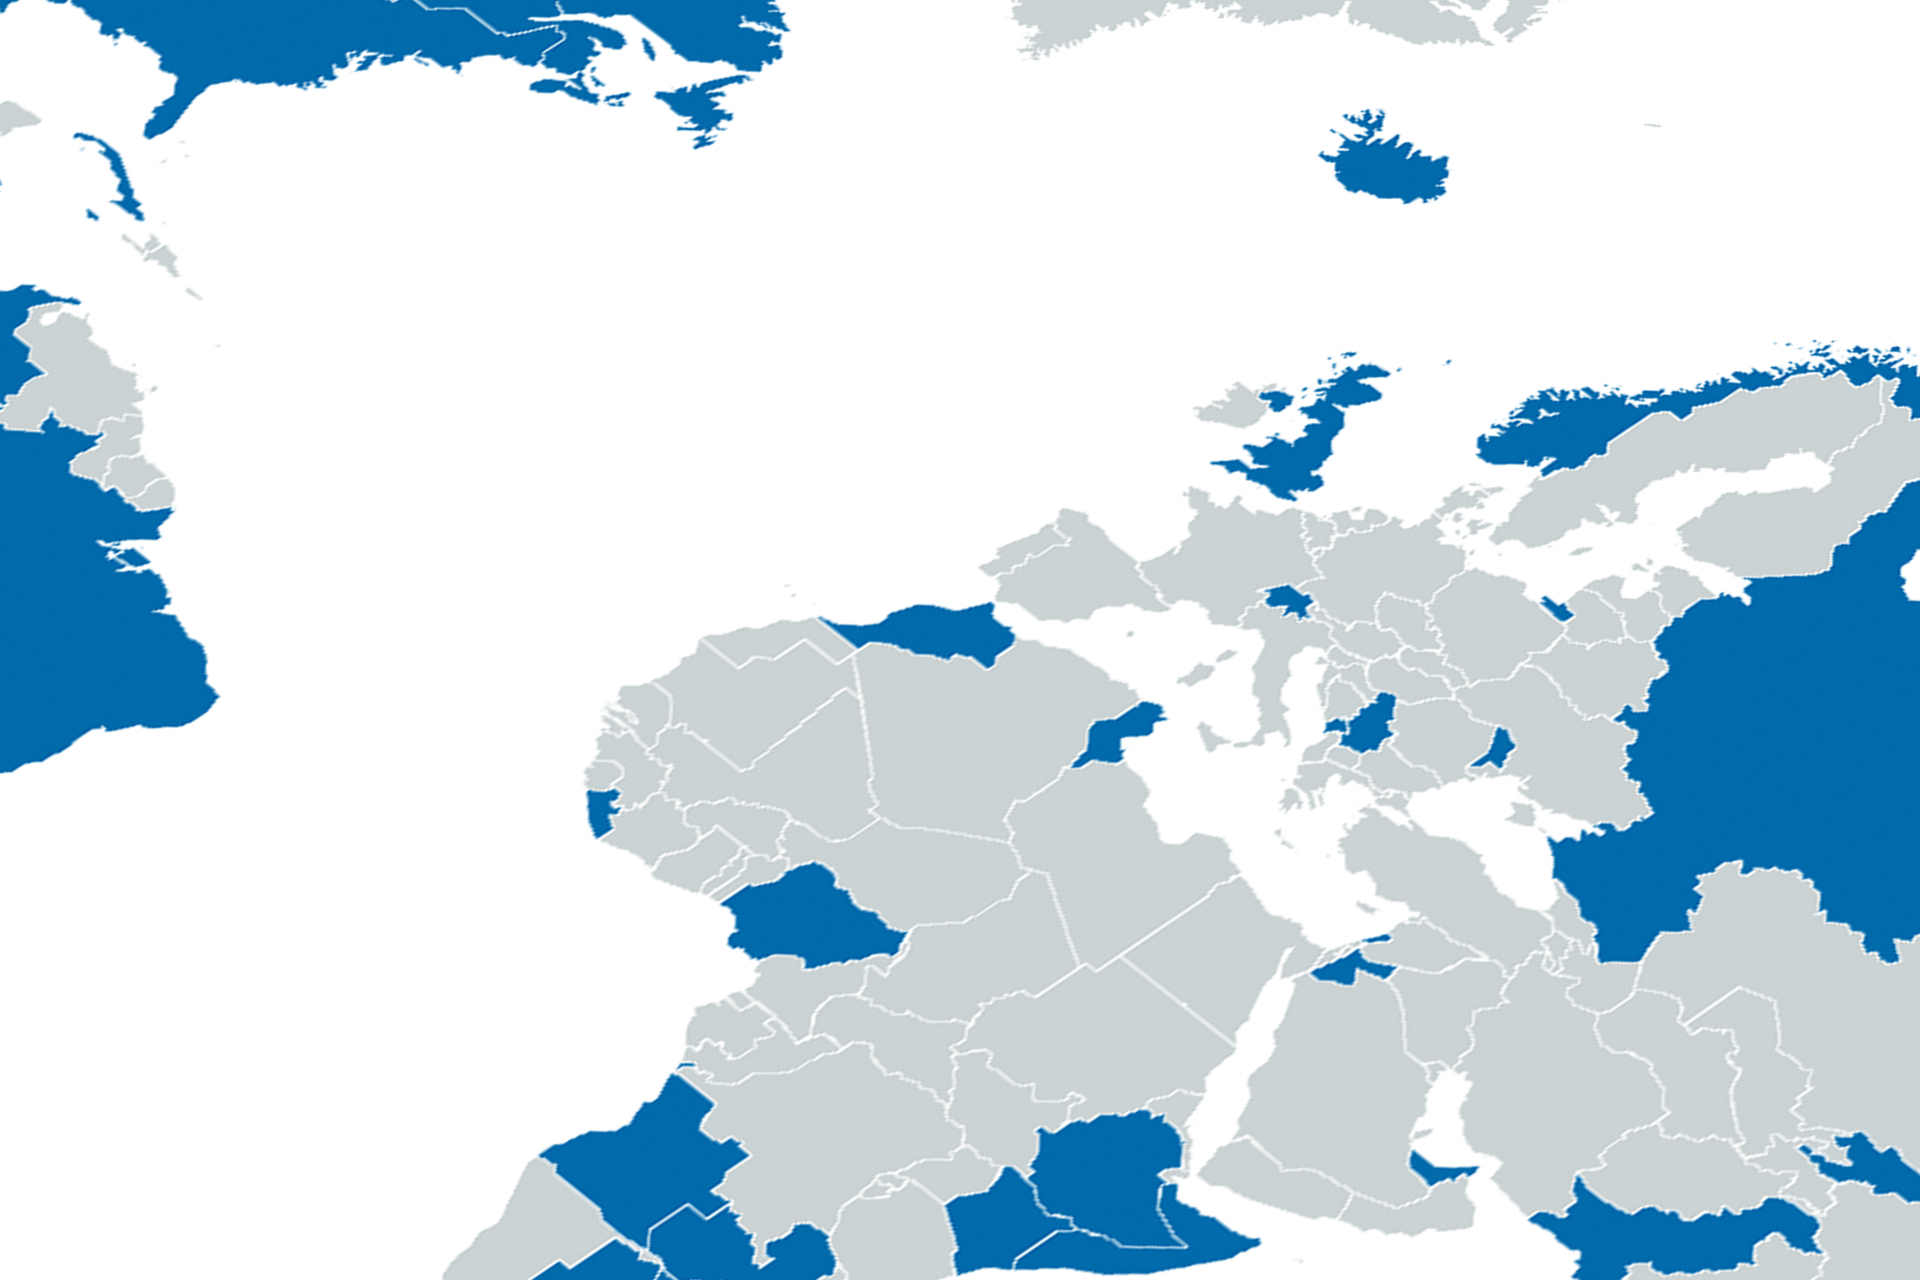
The EV NDC World Map illustrates the global ambition to adopt electric vehicles (EVs) according to the Nationally Determined Contributions (NDCs) submitted by countries under the Paris Agreement. The current edition of the map is based on the NDCs submitted up to 30 September 2026, drawing from the data contained in the NDC Transport Tracker maintained by GIZ and SLOCAT (2025) (v. 4.0).
Our aim is to provide a targeted overview of electric mobility in land transport, assessing the level of ambition in the field internationally while also identifying gaps in policy instruments and measures. This analysis seeks to provide input to both the electric mobility and climate communities, addressing shared priorities as well as industry concerns.
As of 30 September, 151 out of 193 countries (124 countries + 27 EU Member States) had submitted their third NDC. Among them, 77 countries (51 percent) include specific electric mobility targets. This represents a significant increase in ambition, with 61 countries introducing electric mobility goals for the first time, compared to their previous submissions. Our assessment shows a high number of small and developing nations among the NDC 3.0 submissions that contain EV targets.
It is important to note that the analysis is based exclusively on the information contained within the submitted third-generation NDCs. Many countries have additional national strategies, targets and measures detailed in dedicated policy documents, legislation and national plans that may not be fully captured in their NDCs. To reflect these commitments, a separate section compares the targets in the NDCs with those in countries’ long-term low-emission development strategies (LT-LEDS), the Declaration on Accelerating the Transition to 100% Zero Emission Cars and Vans and, where available, national policies.
2. What are NDCs?
Nationally Determined Contributions (NDCs) are national climate action plans that form a central element of the Paris Agreement. They outline a country’s targets and actions to reduce greenhouse gas emissions and adapt to climate impacts, with the collective goal of limiting global temperature rise to well below 2°C while pursuing efforts to limit it to 1.5°C by the end of this century.
The NDC process operates on a five-year submission and updating cycle. While earlier NDCs often laid out actions with a long-term view, many culminating in 2030 targets, the third round, which was originally due in 2025, is the first one to uniformly outline national climate actions with a specific and common implementation horizon through 2035.
This round represents a pivotal juncture, not just because of the decade that has past since the Paris Agreement’s adoption, but because the window to limit global warming to 1.5°C is rapidly closing. The actions taken between 2025 and 2035 will be decisive in determining whether the world can meet this goal. Consequently, the level of ambition in these NDCs is a direct test of countries’ commitment to turning political promises into tangible emission reductions. The updated plans are intended to outline increasingly ambitious action, and they coincide with the phase-out date for the sale of new combustion cars in several jurisdictions.
This cycle is also the first one to be informed by the Global Stocktake (GST), a comprehensive assessment of collective progress. The first GST process, which concluded in 2023, was based on commitments submitted in the run-up to COP26 in 2021. This stocktake underscored the significant gap between existing pledges and what is required to meet the Paris goals, adding further weight to the imperative for enhanced ambition in this round.
2.1 Why focus on electric mobility in transport?
The transport sector represents a critical dimension of the global effort to mitigate climate change. As a primary contributor to greenhouse gas emissions, it accounts for nearly one-quarter of global energy-related CO₂ emissions, with road transport responsible for approximately 75 percent of that share. This significant emissions footprint underscores the urgent need for decarbonisation strategies that can deliver substantial and timely reductions.
Electric mobility stands out as a pivotal near-term strategy to achieve this goal. The International Transport Forum’s (ITF) Transport Outlook 2023 report identifies accelerated action on clean vehicles and fuels as the most impactful lever for decarbonisation. Indeed, this lever accounts for three-quarters of the emission reductions between the ITF’s Current Ambition and High Ambition scenarios.
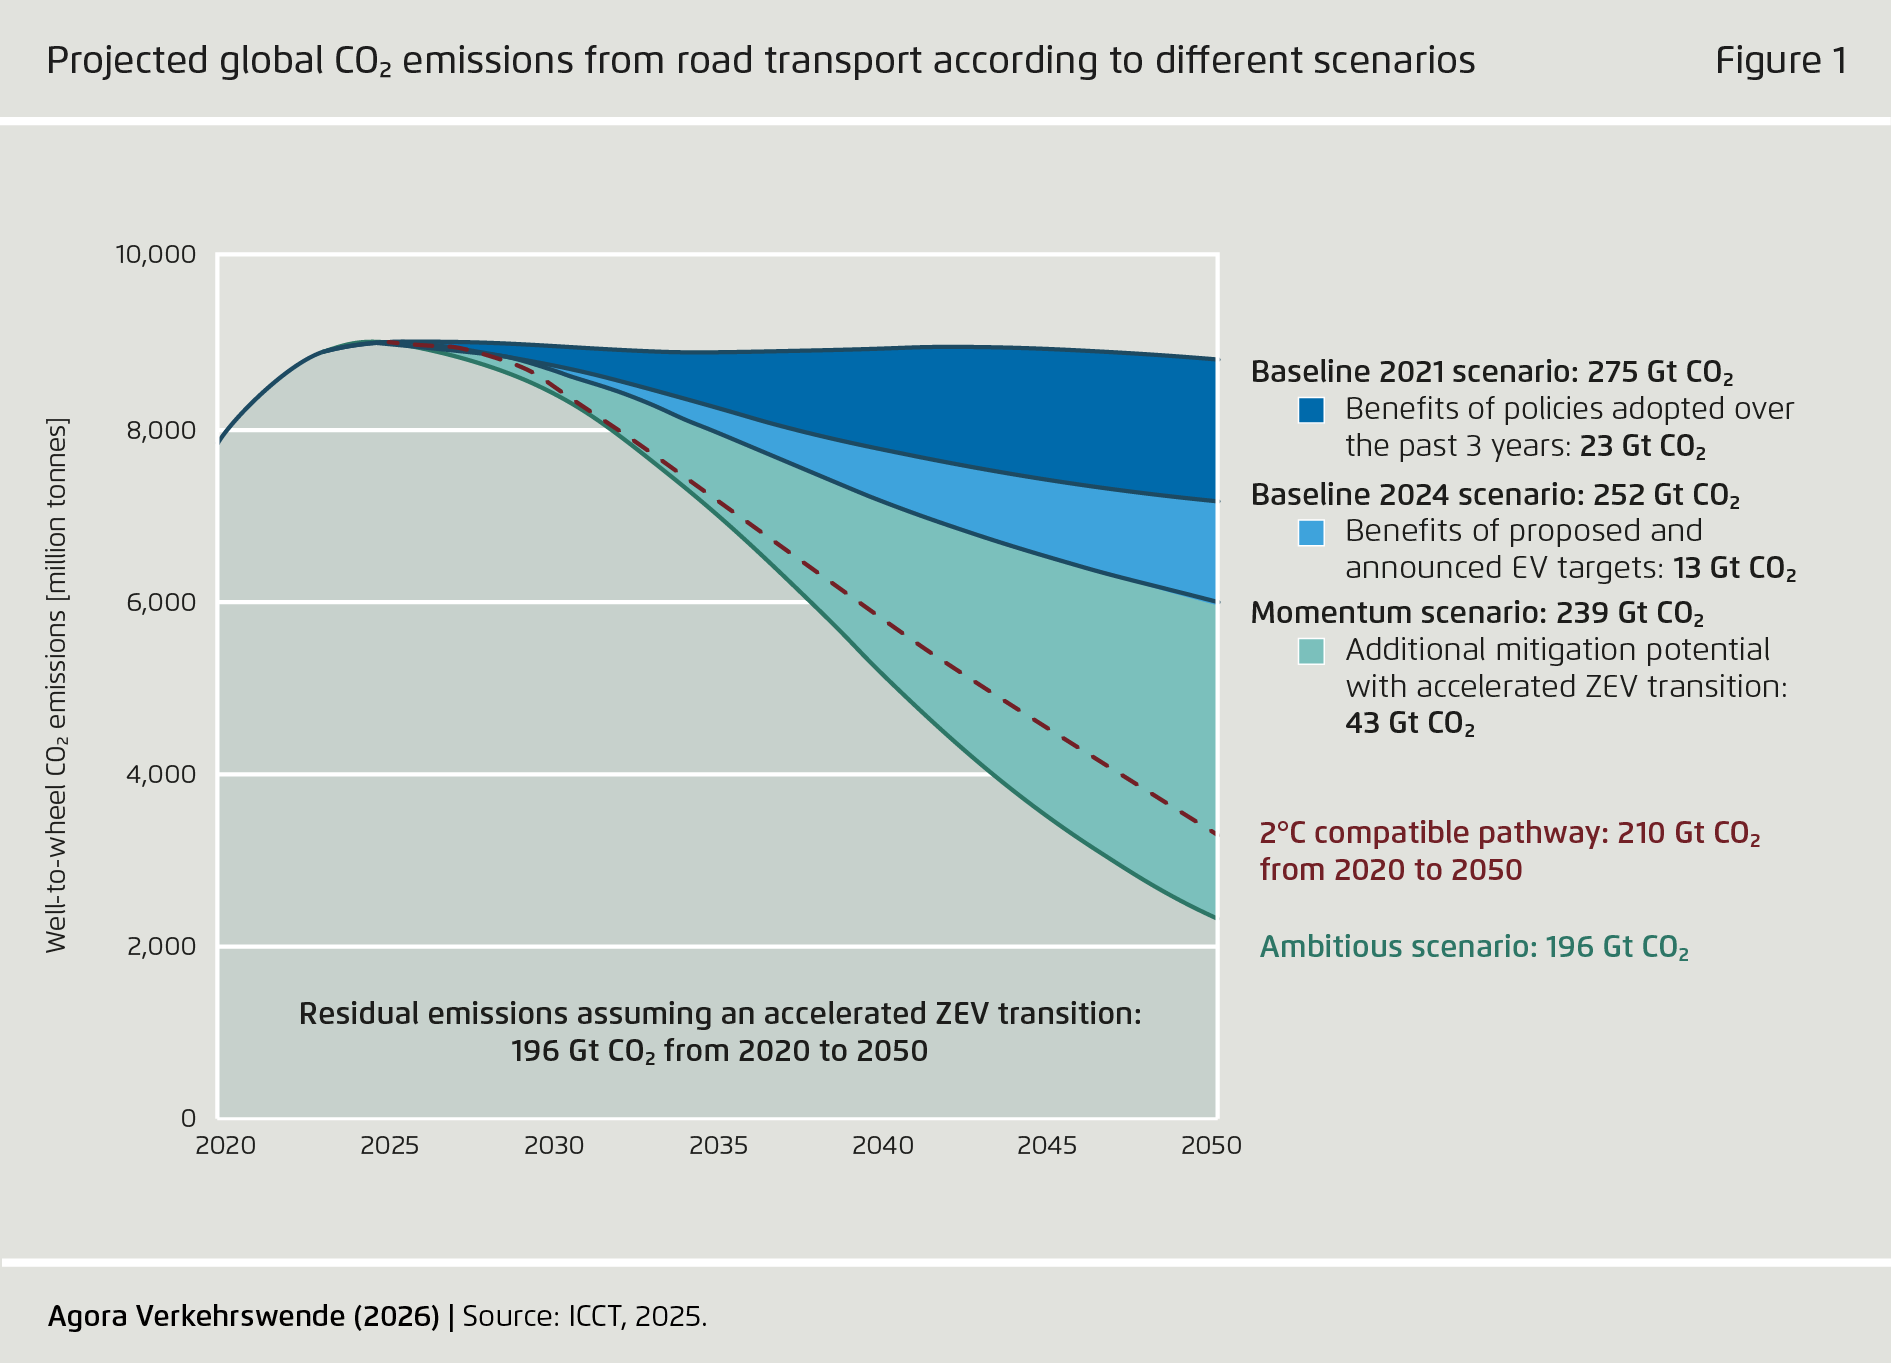
Recent analysis from the International Council on Clean Transportation (ICCT) confirms that the transition to e-mobility is not just a theoretical potential, but is already underway, driven by concrete policy action. The ICCT’s Vision 2050 report shows that policies adopted in major economies over the past few years have significantly improved the emissions outlook, putting global road transport CO₂ emissions on track to peak as early as 2025.
However, this positive momentum should not be taken as grounds for complacency. The same ICCT study serves as a crucial reminder that a significant gap remains between current policy commitments and a trajectory that is aligned with the goals of the Paris Agreement (see Figure 1). Thus, while progress is real, it is not yet sufficient. There is a critical need to not only maintain but drastically accelerate the ambition to adopt electric mobility in national climate plans, including in the latest NDC round.
3. Findings on NDC 3.0 submissions
As of September 2026, 151 countries had submitted their third NDCs, including the European Union, whose NDC sets the course for its 27 Member States.
According to our analysis, 77 countries (51 percent) include specific electric mobility targets in their NDC 3.0 submissions. This represents a significant increase in formal ambition, as 61 countries have introduced electric mobility goals for the first time (compared to prior submissions). Situating this policy ambition within the broader market, countries with NDC-based electric mobility goals now account for more than 65 percent of global car sales.1 A broader view shows that 123 countries have incorporated some form of EV-related policies, measures or announcements, highlighting that while many governments are prioritising the sector, some of them are still lacking the inclusion of concrete, measurable targets.
The push for electric mobility encompasses major markets such as the European Union and China. The regulatory direction for the automotive industry is thus increasingly clear, despite the varying specificity of underlying commitments.
The list of parties with EV targets consists of: Angola, Armenia, Azerbaijan, Bahamas, Bangladesh, Barbados, Belize, Benin, Bolivia, Cambodia, Canada, China (HK), Colombia, Comoros, Congo, Costa Rica, Côte d'Ivoire, Cuba, Eswatini, Ethiopia, European Union, Honduras, Kyrgyzstan, Lesotho, Liberia, Malawi, Mauritania, Mauritius, Moldova, Monaco, Nauru, Nepal, Nigeria, Pakistan, Panama, Palau, Rwanda, Saint Lucia, Samoa, Sao Tome and Principe, Sierra Leone, Singapore, Solomon Islands, South Korea, Sri Lanka, Suriname, Thailand, United Arab Emirates, United Kingdom, Vanuatu and Zambia.
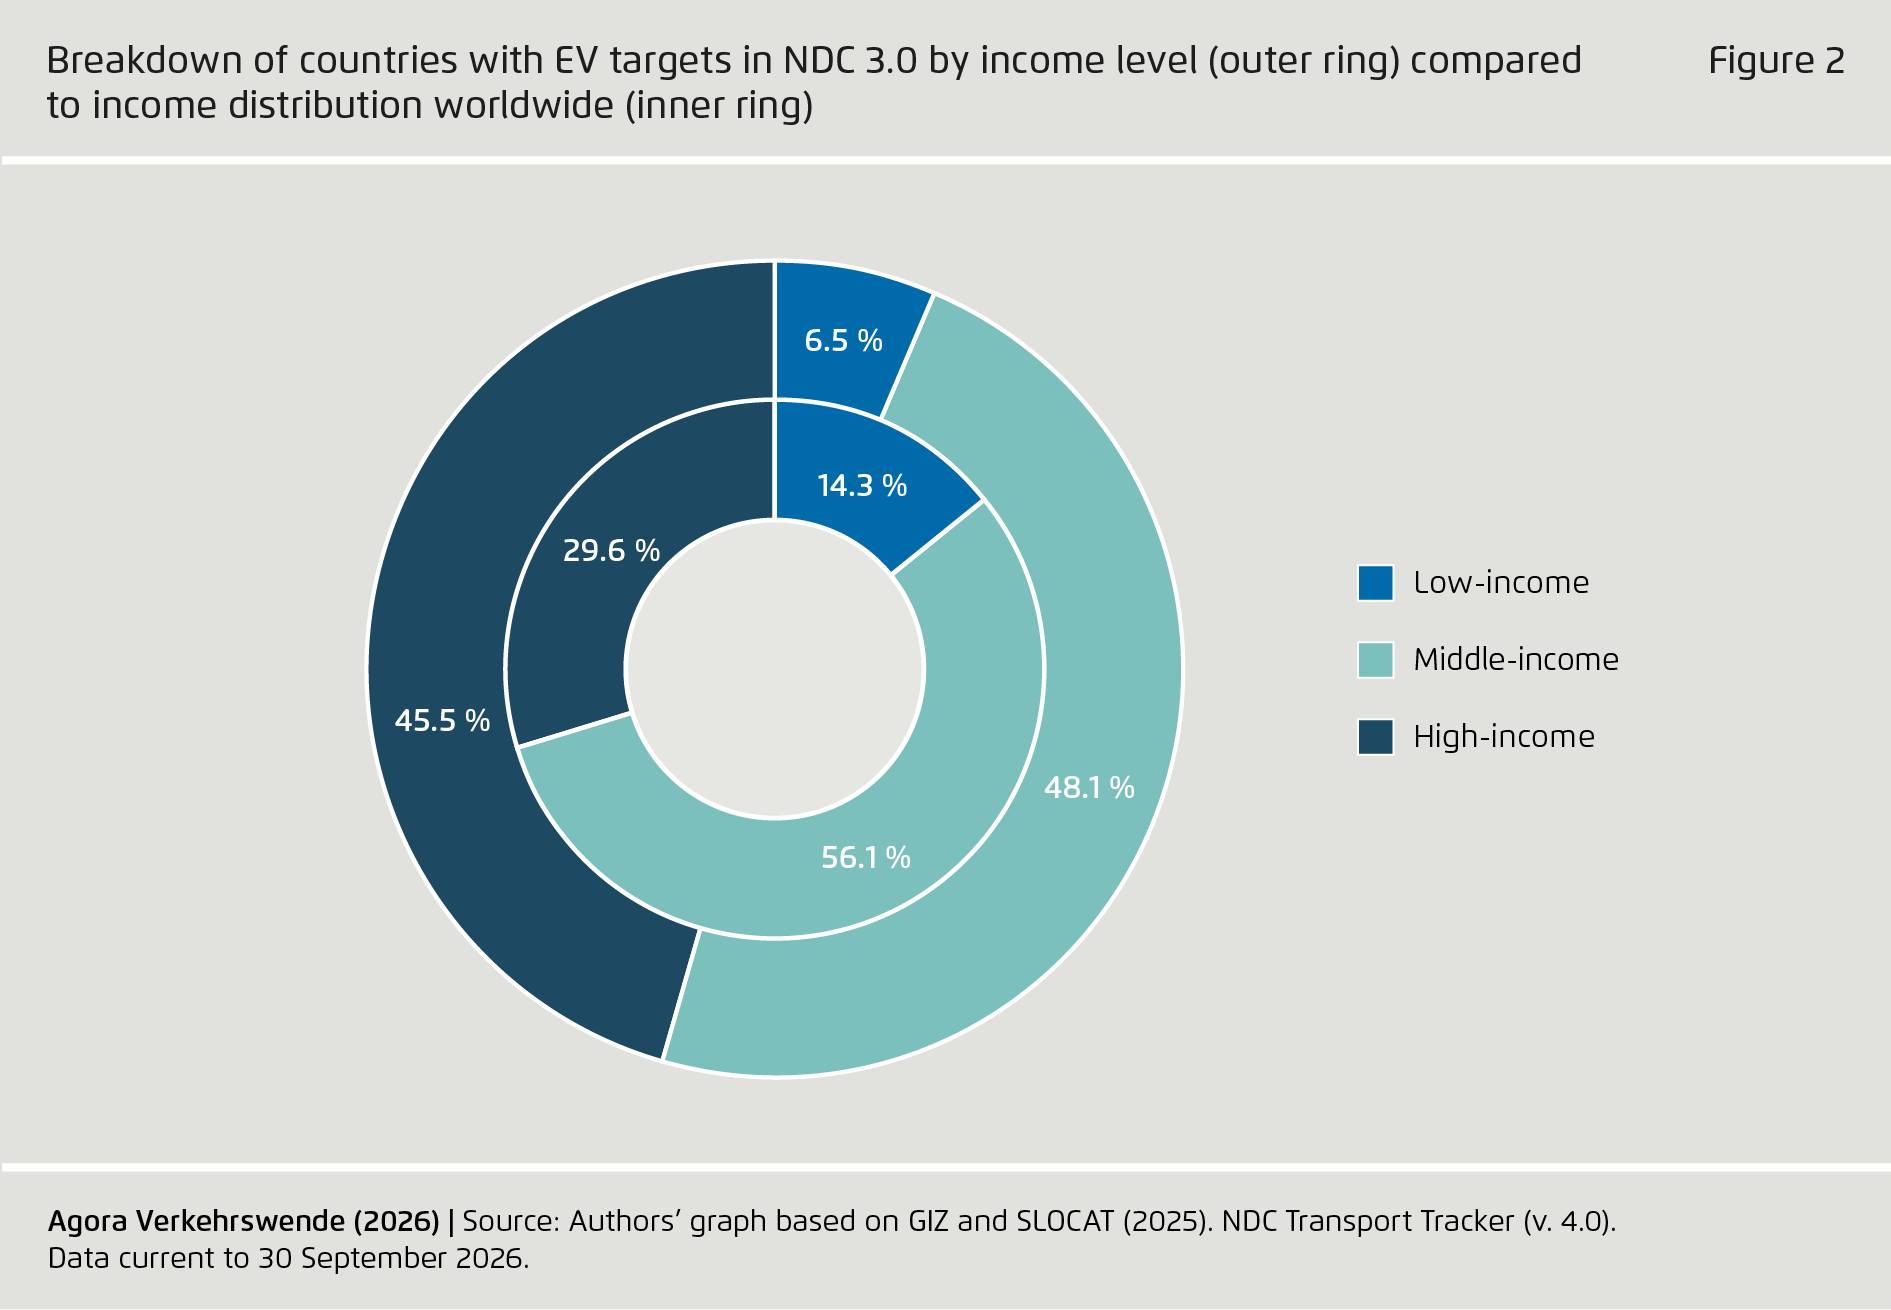
When examining the income-level distribution of countries with EV targets (see Figure 2), high-income nations represent about 46 percent of all countries with EV targets in their NDC 3.0, although they account for roughly 30 percent of all countries globally. This distribution is shaped by the structure of the UNFCCC submissions: the 27 member states of the European Union, which are mostly high-income countries, are represented by a single NDC, which inherently contains an EV target for all of them. The majority of the remaining commitments come from middle-income countries, which constitute about 48 percent of all countries with an EV target. This high rate of participation underscores that for developing countries and emerging economies, the NDC process is a crucial platform for signalling climate priorities and accessing international support.
Despite the political commitment to e-mobility that continues to gain steam among a diverse set of nations, the aggregate climate impact of these commitments remains limited. To date, countries with electric mobility targets in their NDC 3.0 account for just 37 percent of global transport sector GHG emissions. Among the top ten global emitters from the transport sector, Canada, China and the European Union have incorporated a clear EV target in their latest submissions. Major emitters such as the United States, India, Russia and Brazil have thus far omitted such targets.
Our analysis thus reveals two parallel stories in global climate action. First, ambition must expand beyond its current core: high-income leaders like the EU must be joined by other major emitters in formalising clear EV transition targets within their NDCs. Second, the burgeoning commitment from the Global South, evidenced by its high share of NDC submissions and EV targets, must be met with scaled-up international support. This is crucial for bridging the capacity gap, thereby ensuring their growing ambition translates into on-the-ground decarbonisation.
3.1 The most ambitious countries
Among the 77 countries with specific EV targets, some nations stand out by presenting not just percentage targets for electric vehicle (EV) sales, but also broad vehicle-segment coverage. In addition, they show a commitment to complementary infrastructure and industrial policies, and have undertaken detailed financial planning. The next table shows seven nations with particularly strong electric mobility ambitions among NDC 3.0 submissions.
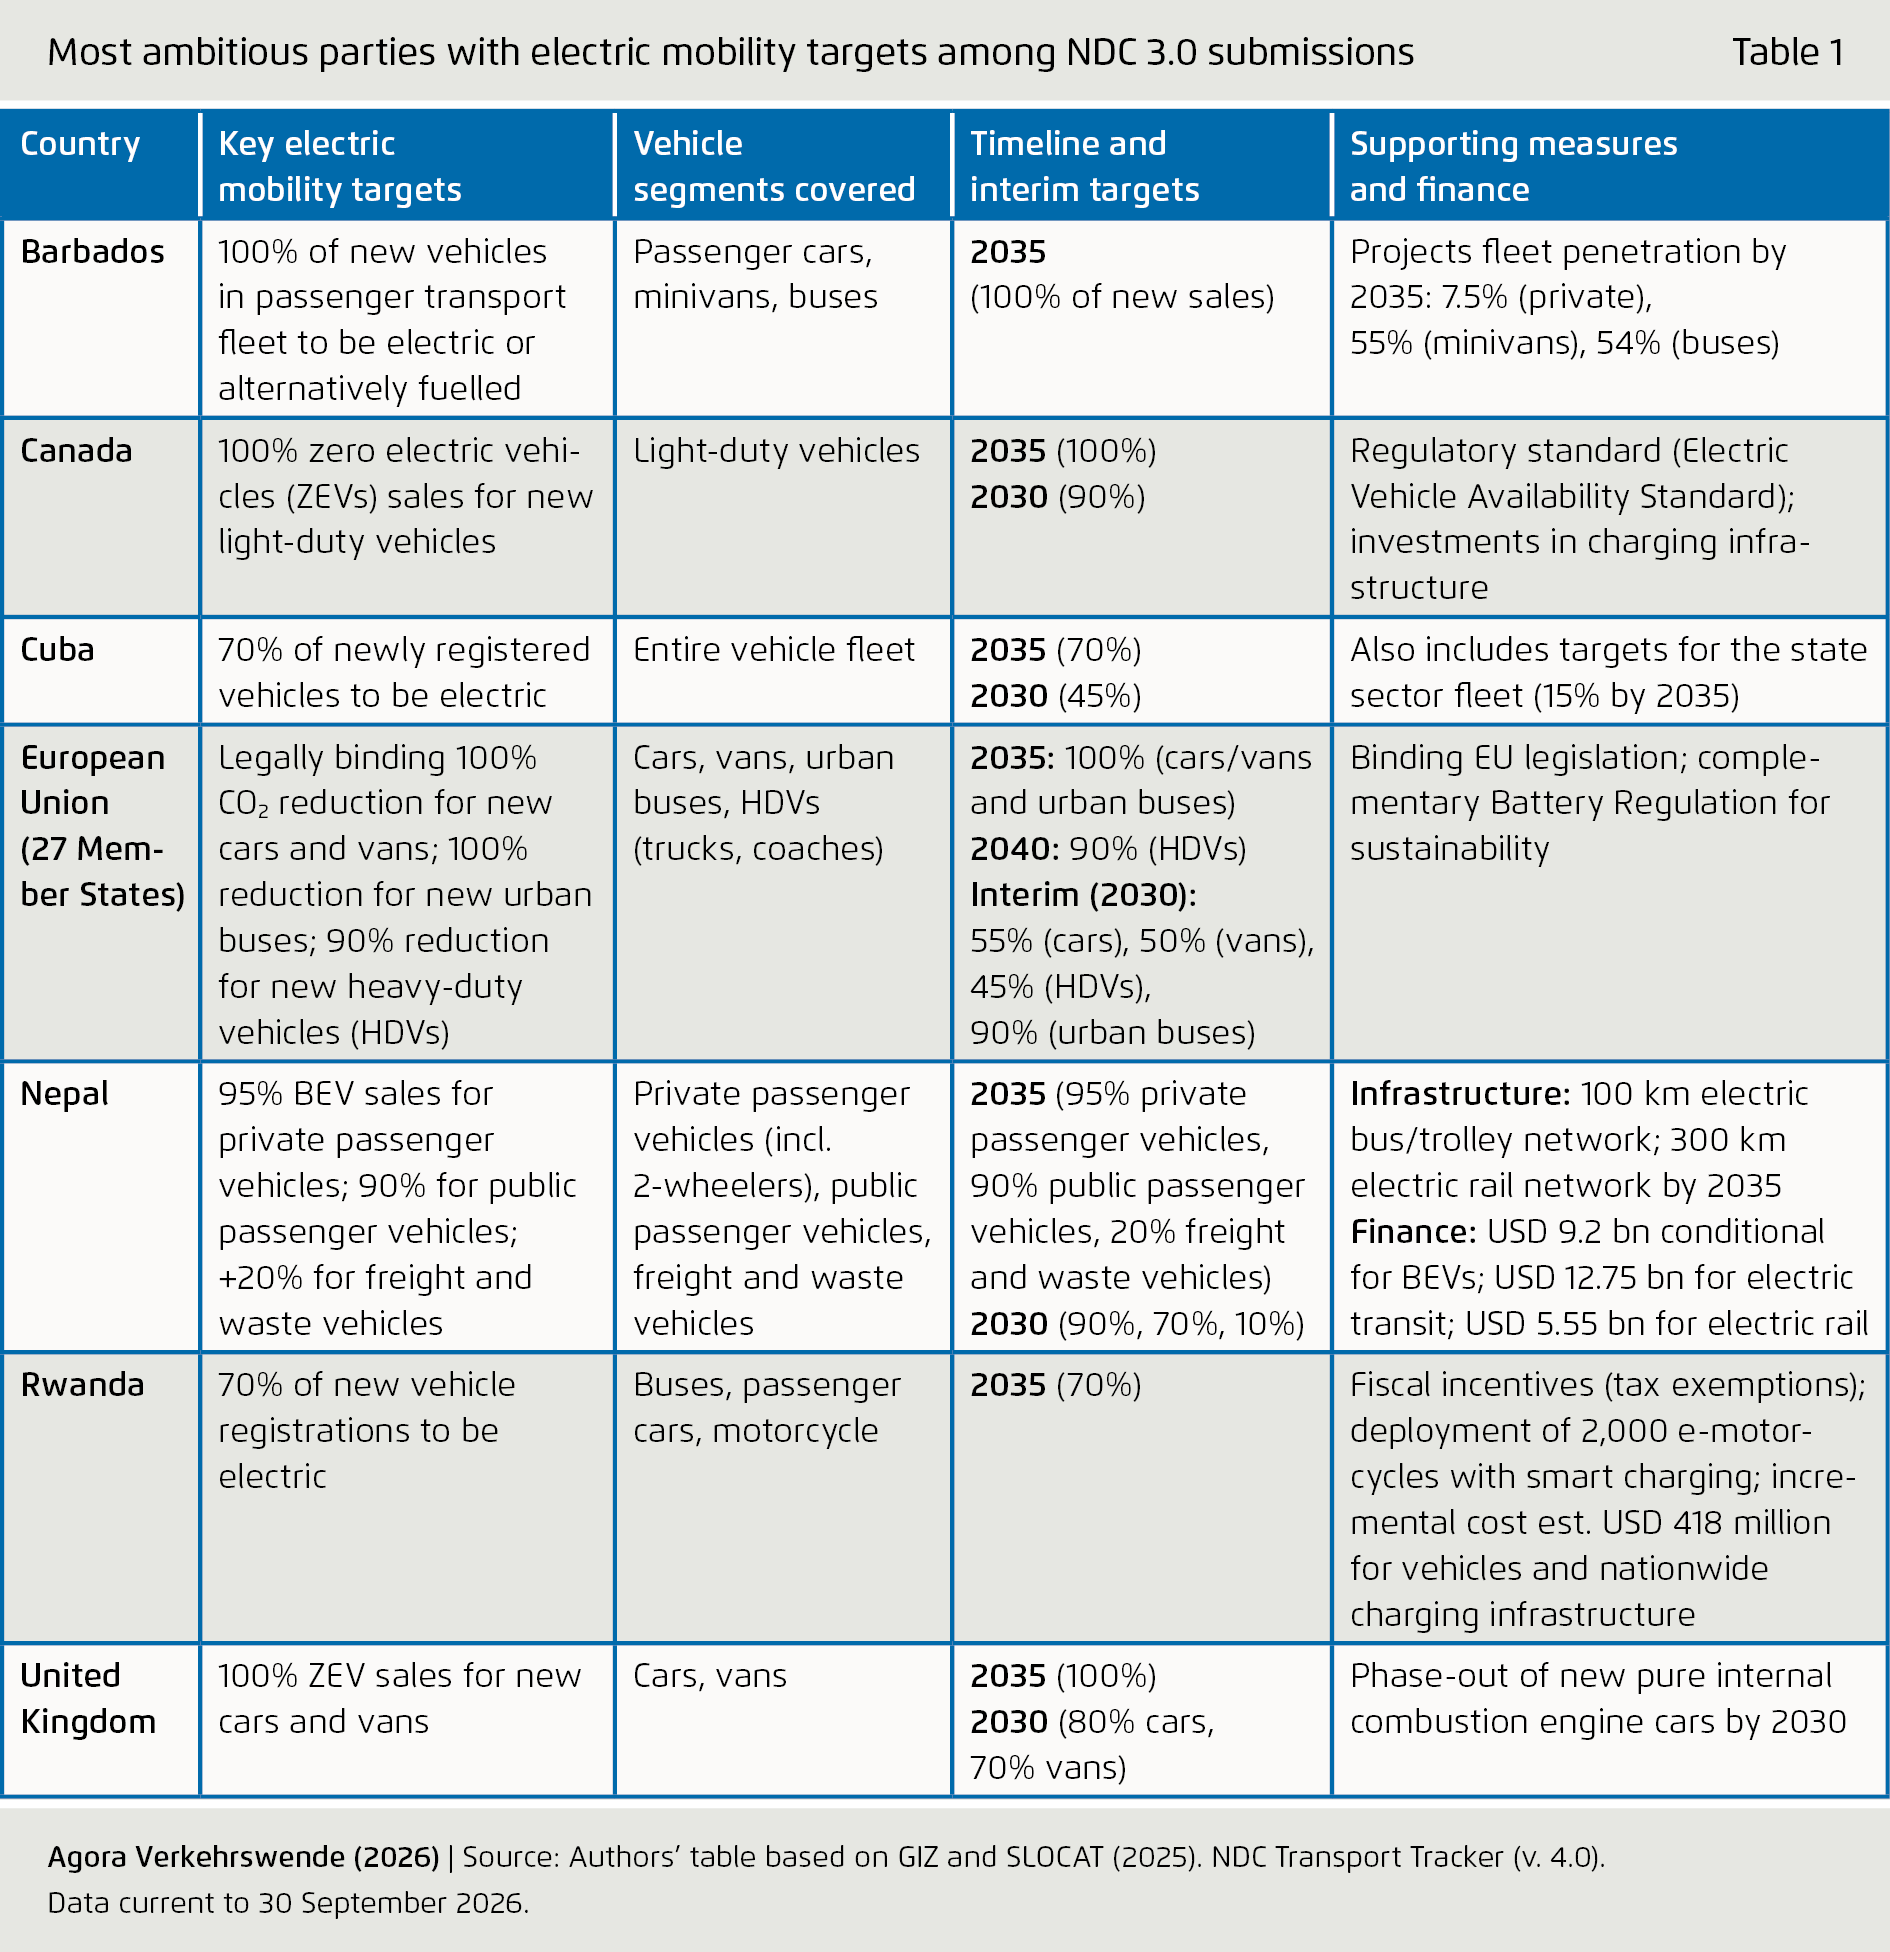
The standout commitments in the NDCs of the European Union, Canada and the United Kingdom are their legislated phase-outs of new internal combustion engine vehicles, thus providing a regulatory framework for a 100-percent zero-emission vehicle (ZEV) market by 2035. However, it must be noted that all three jurisdictions have recently moved to modify implementation in response to ongoing public debate. In the European Union, ongoing legislative revisions backed by the European Commission and a Franco-German compromise are set to ease the 100-percent CO2 reduction mandate by 2035 to 90 percent for passenger cars (and 80 percent for vans, under European Parliament proposals), alongside new compliance flexibilities.
Similarly, the federal government of Canada has formally repealed its mandatory ZEV sales quotas, completely eliminating the 2026 target of 20 percent ZEV sales. This decision was attributed to trade pressures and a desire to reduce the burden on automakers. Meanwhile, the UK government has re-confirmed that from 2030, all new cars must be hybridised or zero-emission, thus explicitly allowing the sale of full hybrids (HEVs) and Plug-in Hybrids (PHEVs) alongside ZEVs until the 2035 deadline. Together, these three cases highlight the dynamic nature of this transition.
Barbados matches this level of ambition with its 2035 100-percent EV mandate for new passenger vehicles. Rwanda has set one of the highest market-share targets globally, aiming for 70 percent of new vehicle registrations to be electric by 2035. Cuba is aiming for 70 percent of newly registered vehicles across segments to be electric by 2035. Nepal emerges as perhaps the most remarkably ambitious developing economy. Its strategy encompasses nearly the entire transport ecosystem, from private cars and two-wheelers to public transport, freight and waste collection vehicles. Crucially, Nepal backs its targets with quantified infrastructure projects and conditional financial plans, demonstrating a sophisticated and costed roadmap for implementation.
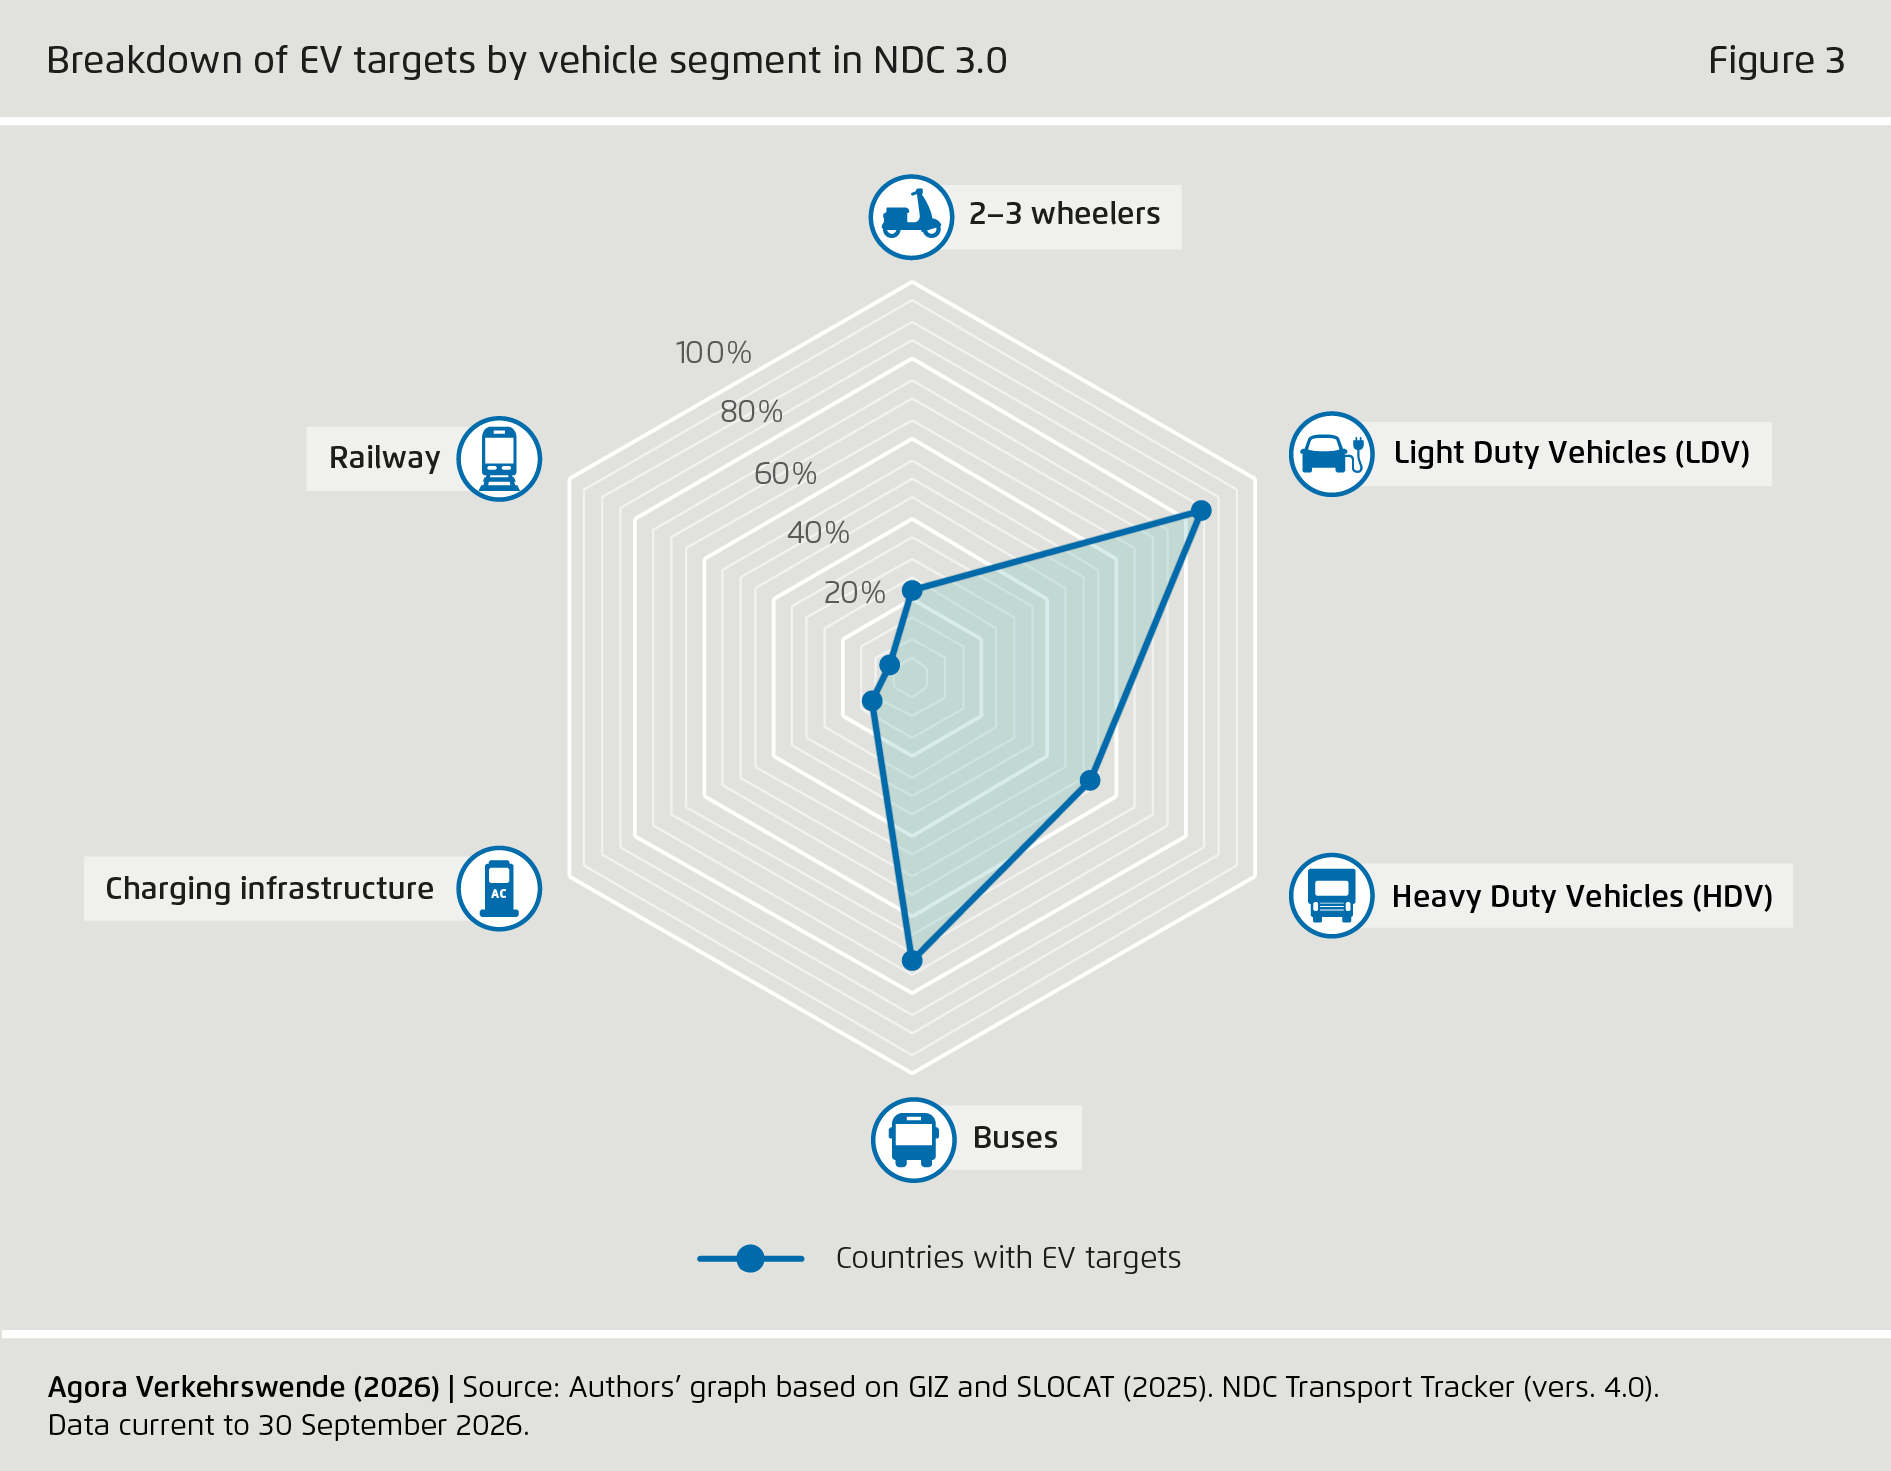
In terms of vehicle segments, light-duty vehicles (LDVs) have a dominant focus among the 77 countries that have submitted NDCs 3.0 with e-mobility targets (see next figure): 65 countries (84 percent) have set targets for those, followed by 55 countries with targets for buses (71 percent), 40 with targets for trucks (52 percent) and 17 for motorcycles and three-wheelers (22 percent). Charging infrastructure, which is a critical enabler of EV adoption, is notably absent from most plans. Only nine countries (China, Côte d'Ivoire, Ethiopia, Liberia, Pakistan, Sao Tome and Principe, Sierra Leone, Suriname and the United Arab Emirates) include specific targets for deploying charging stations.
3.2 Comparing EV ambition in NDC 2.0 and 3.0
A comparative analysis between NDC rounds reveals a landscape of growing ambition. There is a marked increase in specificity and scope between NDC 2.0 and NDC 3.0, with 61 countries articulating their electric mobility targets for the first time (see next figure). The NDCs of countries like Nepal and Belize have evolved from containing general statements or single-measure approaches to comprehensive, multi-faceted strategies. Nepal, for instance, not only increased its 2035 sales targets for public passenger vehicles from 60 to 90 percent but also introduced new targets for freight vehicles and detailed, costed infrastructure projects. This shift from vague policy intentions to measurable outcomes is a critical step for ensuring accountability and attracting investment.
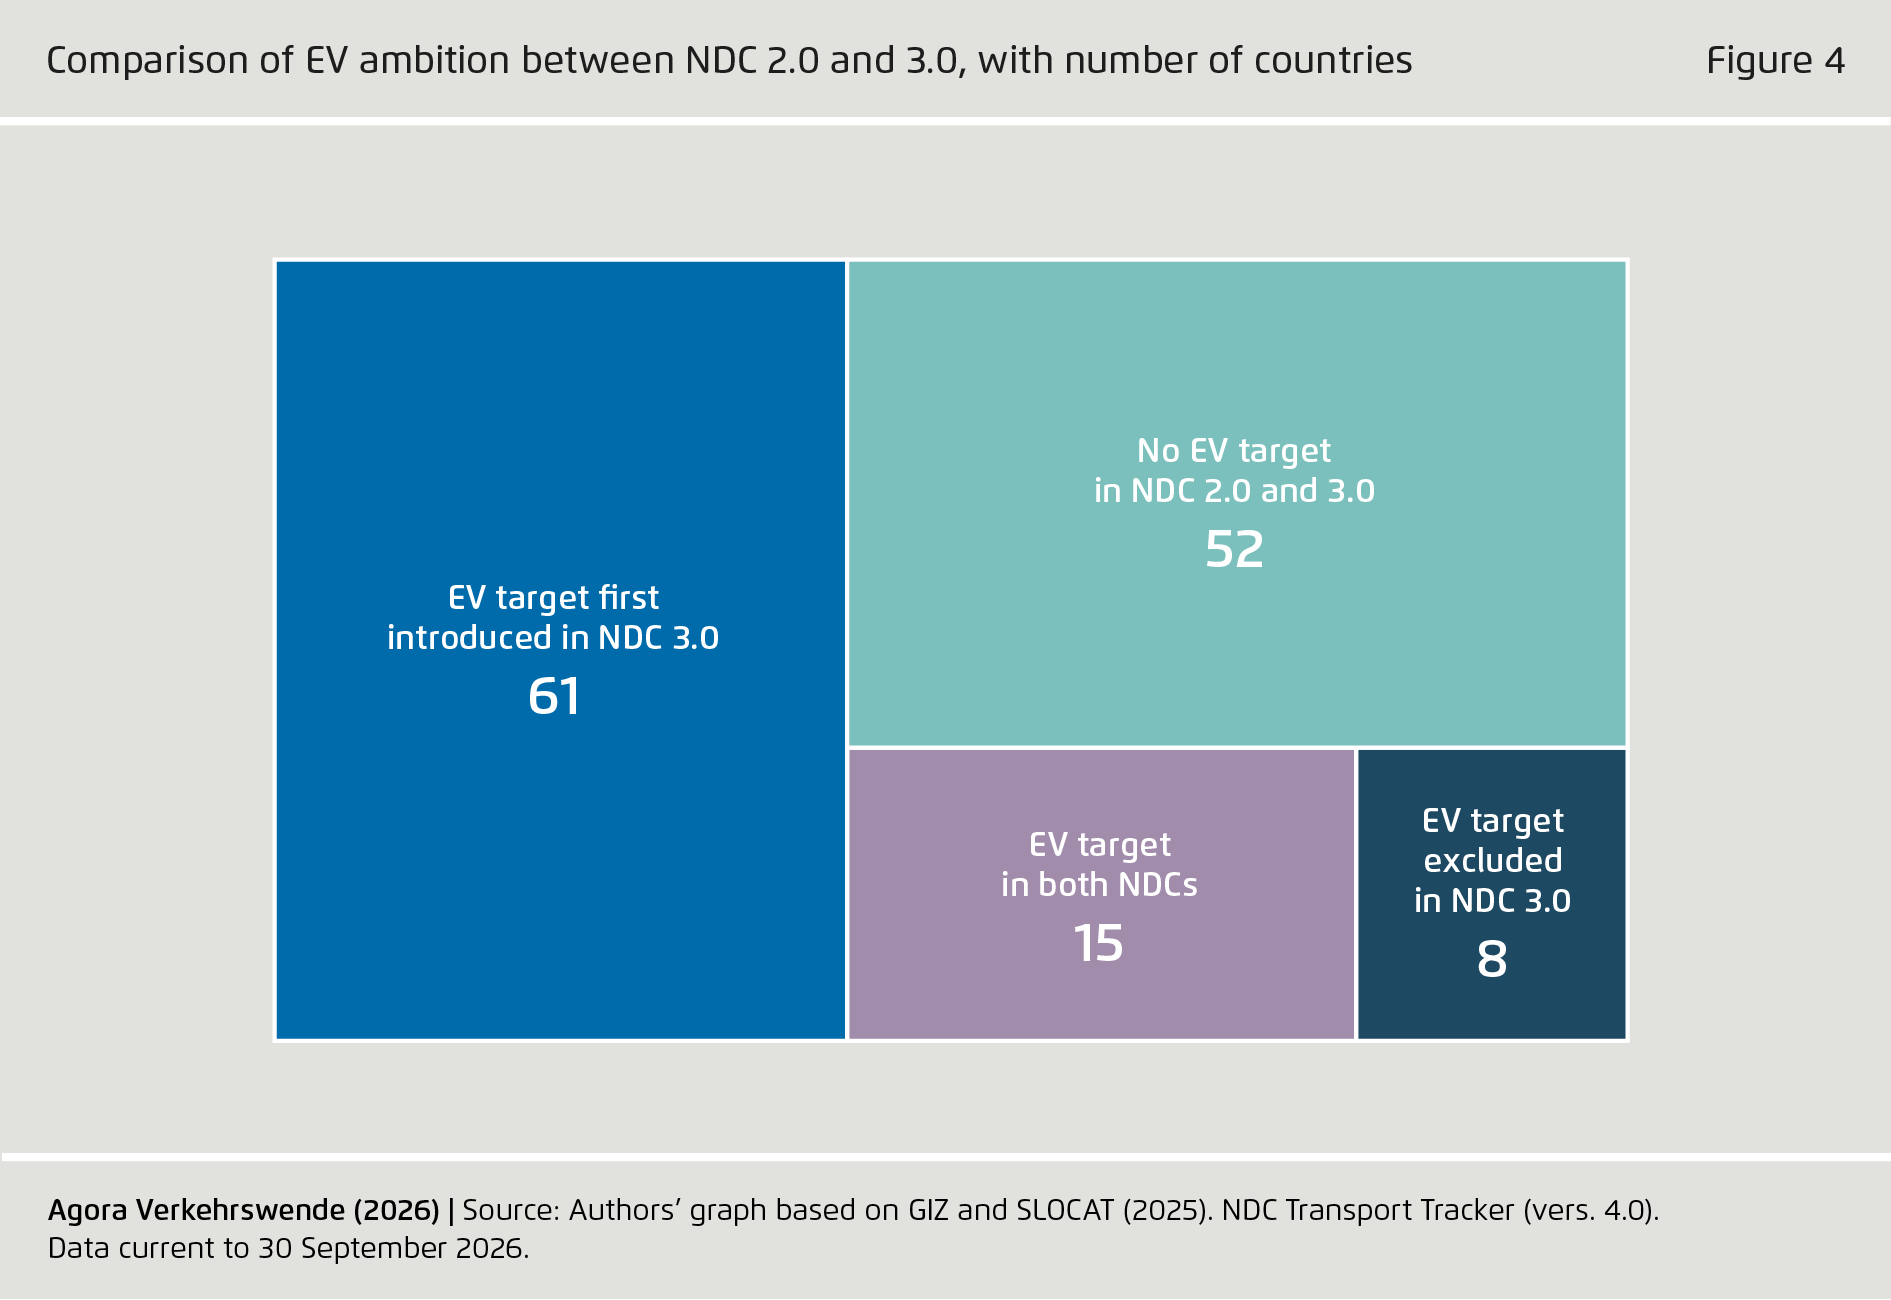
However, this positive momentum is also accompanied by a countervailing trend of diminished ambition. Eight countries – Andorra, Brunei Darussalam, Cabo Verde, Chile, Jordan, Seychelles, Tonga and Uruguay – had established specific EV targets in their NDC 2.0 that are now omitted from their NDC 3.0 submissions. For example, Chile has removed its previous target of achieving 100 percent electric taxis and public transport, while Uruguay has withdrawn its goal of achieving a 30 percent share of electric vehicles in new car sales by 2030. These commitments had previously sent clear and valuable signals to the market.
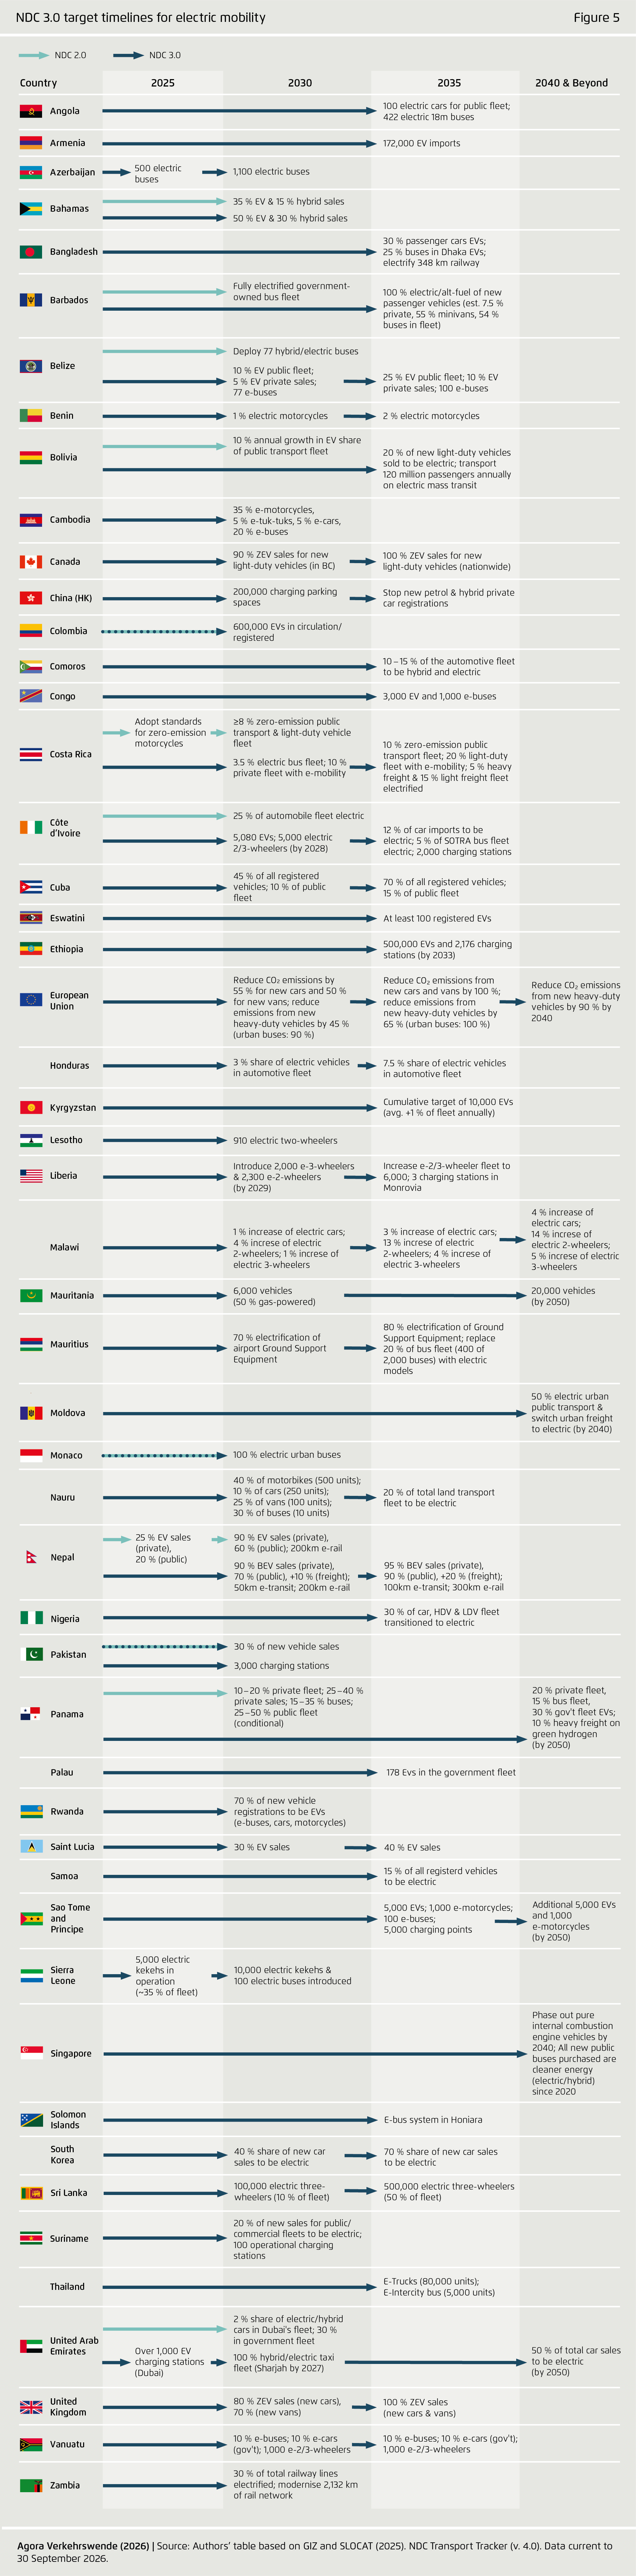
The following timetable provides a visual overview of national targets across all parties with EV targets in the new round of NDCs.
3.3 Policies supporting EV market uptake
Following the prior section’s assessment of national electric mobility targets, this section analyses the policy measures and implementation pathways outlined in the NDCs to achieve declared ambitions. Put simply, targets define the “what” and “when”, while policies describe the “how”. We classify policy commitments using a three-tiered scale that ranges from highly specific and actionable measures (Tier 1) to generic and aspirational statements (Tier 3). This categorisation reveals clear patterns regarding the global readiness to implement the transition to zero-emission transport technologies. Our policy Tiers are as follows:
Concrete and actionable measures (Tier 1): Policy instruments that specify how part of the transition will be delivered and meet at least one verifiable criterion: (a) a funding amount, budget or cost estimate tied to the measure; (b) a regulation, standard or fiscal measure with a stated deadline, phase-in or duration, including cases where a target has been translated into binding regulation; or (c) a named programme or project with quantified scope or a delivery timeline. Deadlines attached only to studies or policy design do not qualify. Examples include Barbados, which extended its excise and VAT holiday on electric vehicles “for an additional two years until March 2026”. Canada’s Electric Vehicle Availability Standard turns its zero-emission sales target into a binding regulation. Costa Rica costs its 52 km electric passenger railway at US$800 million, with milestones for 2027 and 2030. Nauru has budgeted US$2.2 million for electric buses and chargers. Palau is planning an electric bus system starting in 2026 that will reach full scale by 2031. Rwanda will roll out 2,000 e-motorcycles with smart charging stations between 2025 and 2030. Vanuatu has earmarked US$11.5 million for its e-mobility policy. EU member states fall into this category through EU-level legislation. These measures are concrete and amenable to monitoring, and they give the clearest signals to the market.
Implementation-focused measures (Tier 2): The NDC identifies a concrete action or enabling condition (a type of incentive, charging infrastructure, public procurement or fleet replacement, a pilot, a regulation without a deadline, or a named strategy, plan or roadmap) but gives no amount, quantity or deadline. For instance, Angola is planning nationwide charging infrastructure, fiscal incentives and electric bus pilots in Luanda. Jordan is establishing a nationwide fast-charging network with tax incentives. Maldives is combining EV incentives with the expansion of charging infrastructure and battery-swapping facilities. Cuba is prioritising EV acquisition through import-tariff exemptions. While these pledges show a defined pathway, without amounts, quantities or deadlines it is hard to monitor the speed and scale of implementation.
Generic and aspirational declarations (Tier 3): Statements of intent using non-specific verbs (promote, encourage, develop, accelerate) without an identifiable instrument. Under this category we find policies from countries such as Botswana (“provide incentives”), Belarus (“develop electric transport”), Burundi (“promotion of electric mobility”), Brazil (“replacing fossil fuels with electricity”) and Eritrea (which only mentions “electric two-wheelers”). While they indicate political support for the energy transition, clear adoption targets and metrics for verifying success are missing, thus limiting confidence in meaningful policy execution or outcomes.
Among the 151 countries that submitted NDC 3.0, 123 (81 percent) have some form of EV policy. Within this subset, 37 percent of nations fall under Tier 1. In this group, both developed and developing countries, such as the European Union, Barbados, Rwanda and Costa Rica, are setting the standard with concrete, time-bound and quantified targets for vehicle adoption, fleet renewal and fiscal measures.
However, the largest group of countries falls under Tier 2 (48 percent), while a further 15 percent come under Tier 3 with purely aspirational statements; taken together, these two Tiers account for nearly two-thirds of all countries with EV policies. Accordingly, while most countries present strategic plans that clearly outline “what” needs to be done, such as developing national strategies, launching pilot corridors, and introducing incentives, the majority neglect the question of “how much by when” — a crucial component of actionable policy. This implementation gap is compounded by a critical blind spot: the under-specification of charging infrastructure. With very few exceptions, national vehicle adoption goals are not matched by explicit, quantified and funded targets for the deployment of public and private charging networks, revealing a potentially critical bottleneck for the envisioned rollout of electric mobility.
4. Alignment with existing international EV commitments
NDCs are being submitted in a context of existing international commitments within and beyond the United Nations Framework Convention on Climate Change (UNFCCC). In the following, we assess the ambition of EV targets in NDC 3.0 in relation to Long-Term Strategies (LTS), which provide a mid-century vision, and the 2021 Zero Emission Vehicles (ZEV) Declaration, which sets a clear phase-out date for light-duty ICEV sales.
4.1 Alignment with Long-Term Strategies (LTS)
Parties to the Paris Agreement are invited to submit Long-Term Strategies (LTS), or long-term low greenhouse gas emission development strategies, to complement the ten-year time horizon of NDCs with a long-term vision. They are a crucial indicator of countries’ commitments to reach net-zero GHG emissions by mid-century and thereby keep the Agreement’s targets within reach.
Of the 88 countries which have submitted LTS (most of them between 2020 and 2024), 52 include specific EV targets. The following table details how EV targets have been carried forward, or, in some cases, omitted, between a country’s LTS and its latest NDC.
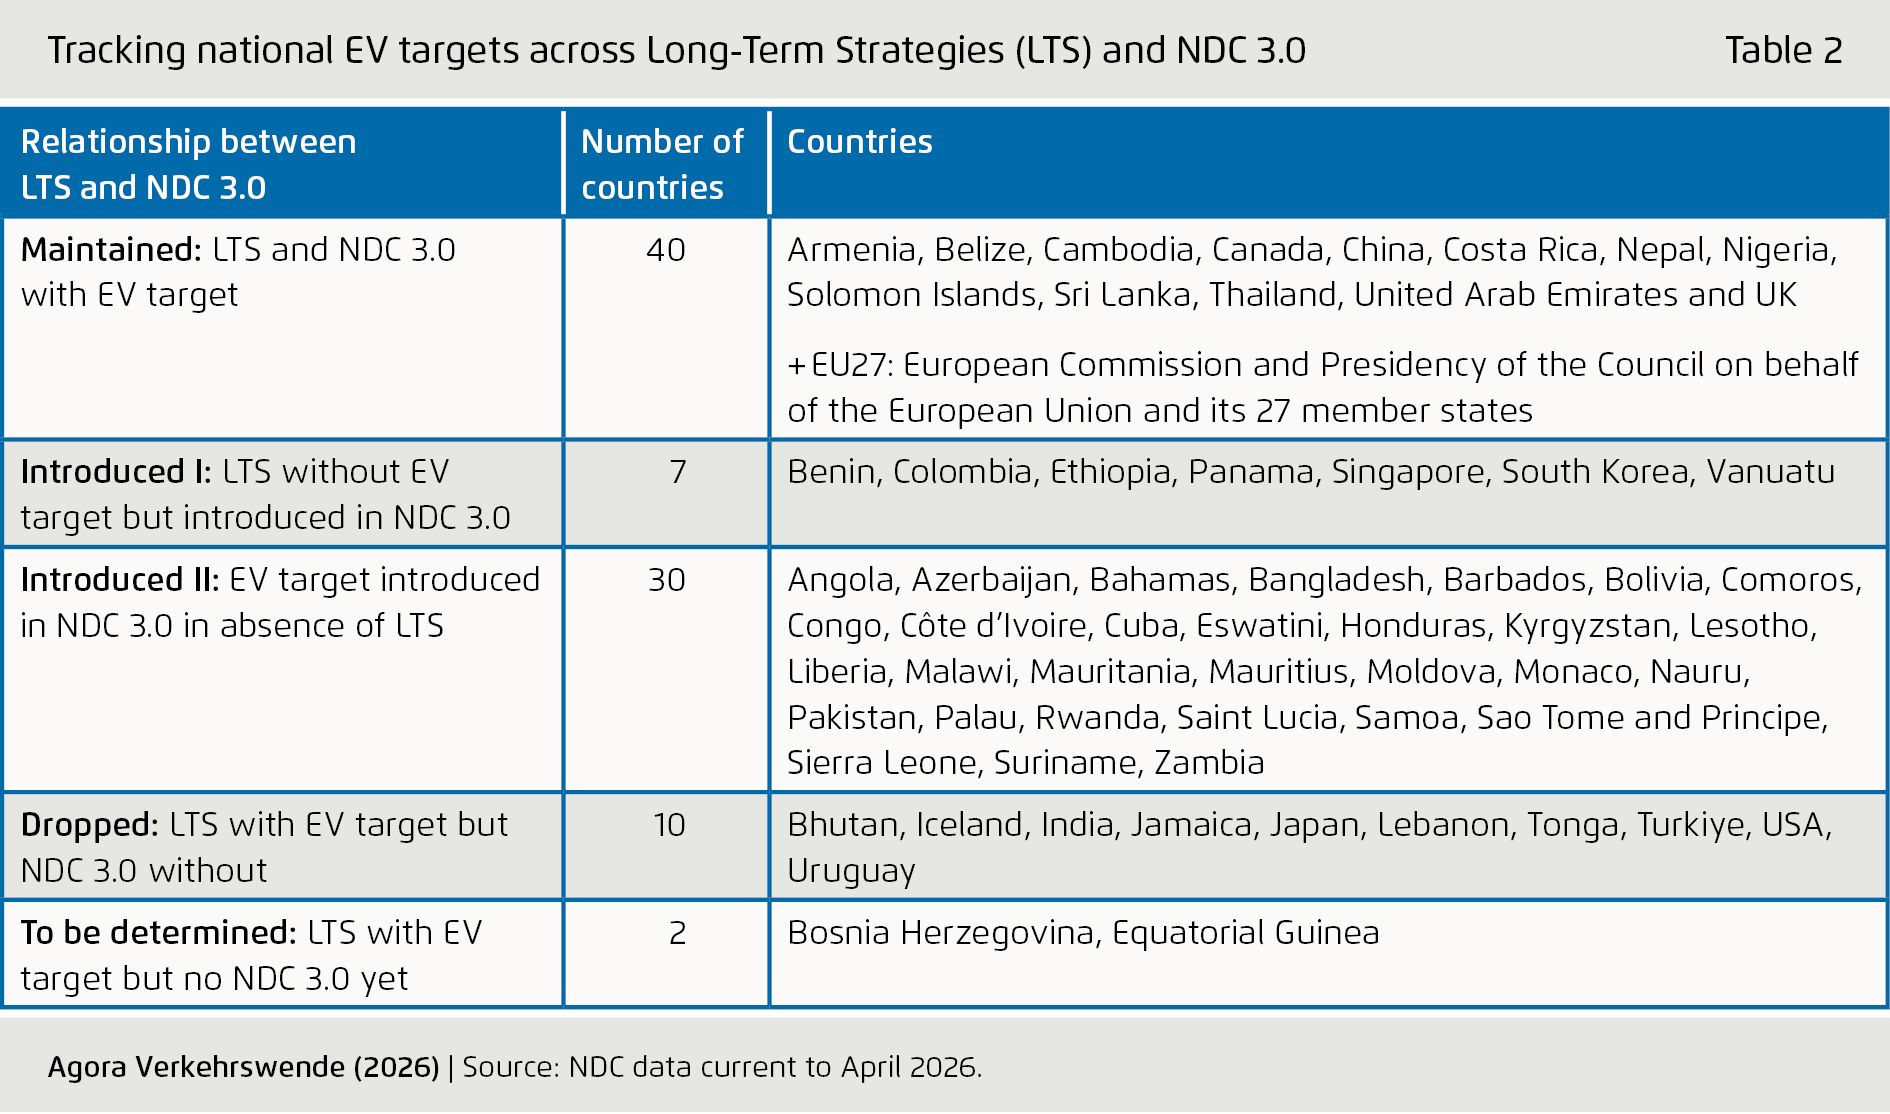
With the exception of Armenia, Bosnia Herzegovina and Equatorial Guinea, all countries with EV targets in their LTS submitted an NDC 3.0. Some 77 percent thereof maintained an EV target in their latest NDC, while 23 percent dropped their target.
Overall, policymakers and the broader public are increasingly aware of the important role of electric mobility for climate change mitigation, particularly in the transport sector. While EV adoption has surged in recent years thanks in part to technological improvements and declining costs, further progress in fleet electrification is becoming increasingly salient as the time horizon for action shifts from mid-century (for LTS) to 2035 (for third-round NDCs). With EV markets maturing just as it becomes ever more necessary to end the sale of combustion engine vehicles, the 2030s will be decisive for reaching net zero by mid-century, not least given the 15-year average life span of passenger cars.
4.2 Alignment with the Zero-Emission Vehicle (ZEV) Declaration
The ZEV Declaration, launched at COP26 in 2021, aims for all new car and van sales to be zero emission by 2035 in leading markets and by 2040 globally. At COP26, 31 national governments signed the Declaration, which marks a significant forward step in the effort to phase out the sale of new internal combustion engine vehicles (ICEVs) in the light-duty segment. As of October 2026, 44 national governments have adopted the Declaration.
As the Declaration was launched, many countries had either already submitted their NDC 2.0 or only decided to sign up at a later stage. Accordingly, the 17 EU signatories were the only ones to include a ZEV-compatible phase-out target. In this way, the third NDC round can be seen as a litmus test for the implementation of the ZEV Declaration – as the first target year, 2035, coincides with the time horizon of the NDC 3.0.
Among the 25 signatory countries to the ZEV Declaration (plus the 17 EU member states collectively) that have submitted a new NDC, only a few have included a national ICE phase-out target that is aligned with the Declaration's ambition. Specifically, the targets outlined in the NDCs of the European Union, Canada and the United Kingdom are compatible with the 2035 goal. Other signatories, such as Colombia and Nigeria, have set only partial electrification targets in their NDCs that fall short of a full phase-out. This indicates that for many countries, the ZEV Declaration remains a standalone political commitment that has not yet been operationalised into their formal climate strategy.
It is crucial to recognise that a country’s climate ambition is not defined solely by its NDC or its endorsement of international declarations. Significant policy developments often occur at the national level, through domestic legislation, sectoral strategies, or sub-national regulations, which may not be fully captured in international submissions. For instance, Uganda, an emerging economy which is not a signatory to the ZEV Declaration, has nevertheless established a robust domestic target of 100-percent electric passenger car sales by 2040, as well as targets for bus and two- and three-wheeler electrification as early as 2030.2 Similarly, in 2024 Ethiopia enacted a more immediate measure, banning the import of internal combustion engine light-duty vehicles. In the absence of domestic vehicle manufacturing, this effectively functions as a 100 percent EV sales mandate. These examples demonstrate that the absence of an explicit commitment in international policy contexts should not be equated with the absence of national action or intent.
5. Alignment with EV national policies
While the NDCs are the main instrument for communicating international climate ambition under the Paris Agreement, they have an overarching, economy-wide reach rather than a transport-specific one, and they are not legally binding at the national level. Therefore, many governments define their transport electrification goals with domestic legislation, sectoral roadmaps or national plans without transferring them into their NDCs. Including the national policy alongside NDCs is therefore essential to capture the full scope of EV ambition, evaluate whether international pledges are backed by binding domestic law and identify where international climate reporting lags behind domestic policy reality.
5.1 Coverage across NDCs and domestic policies
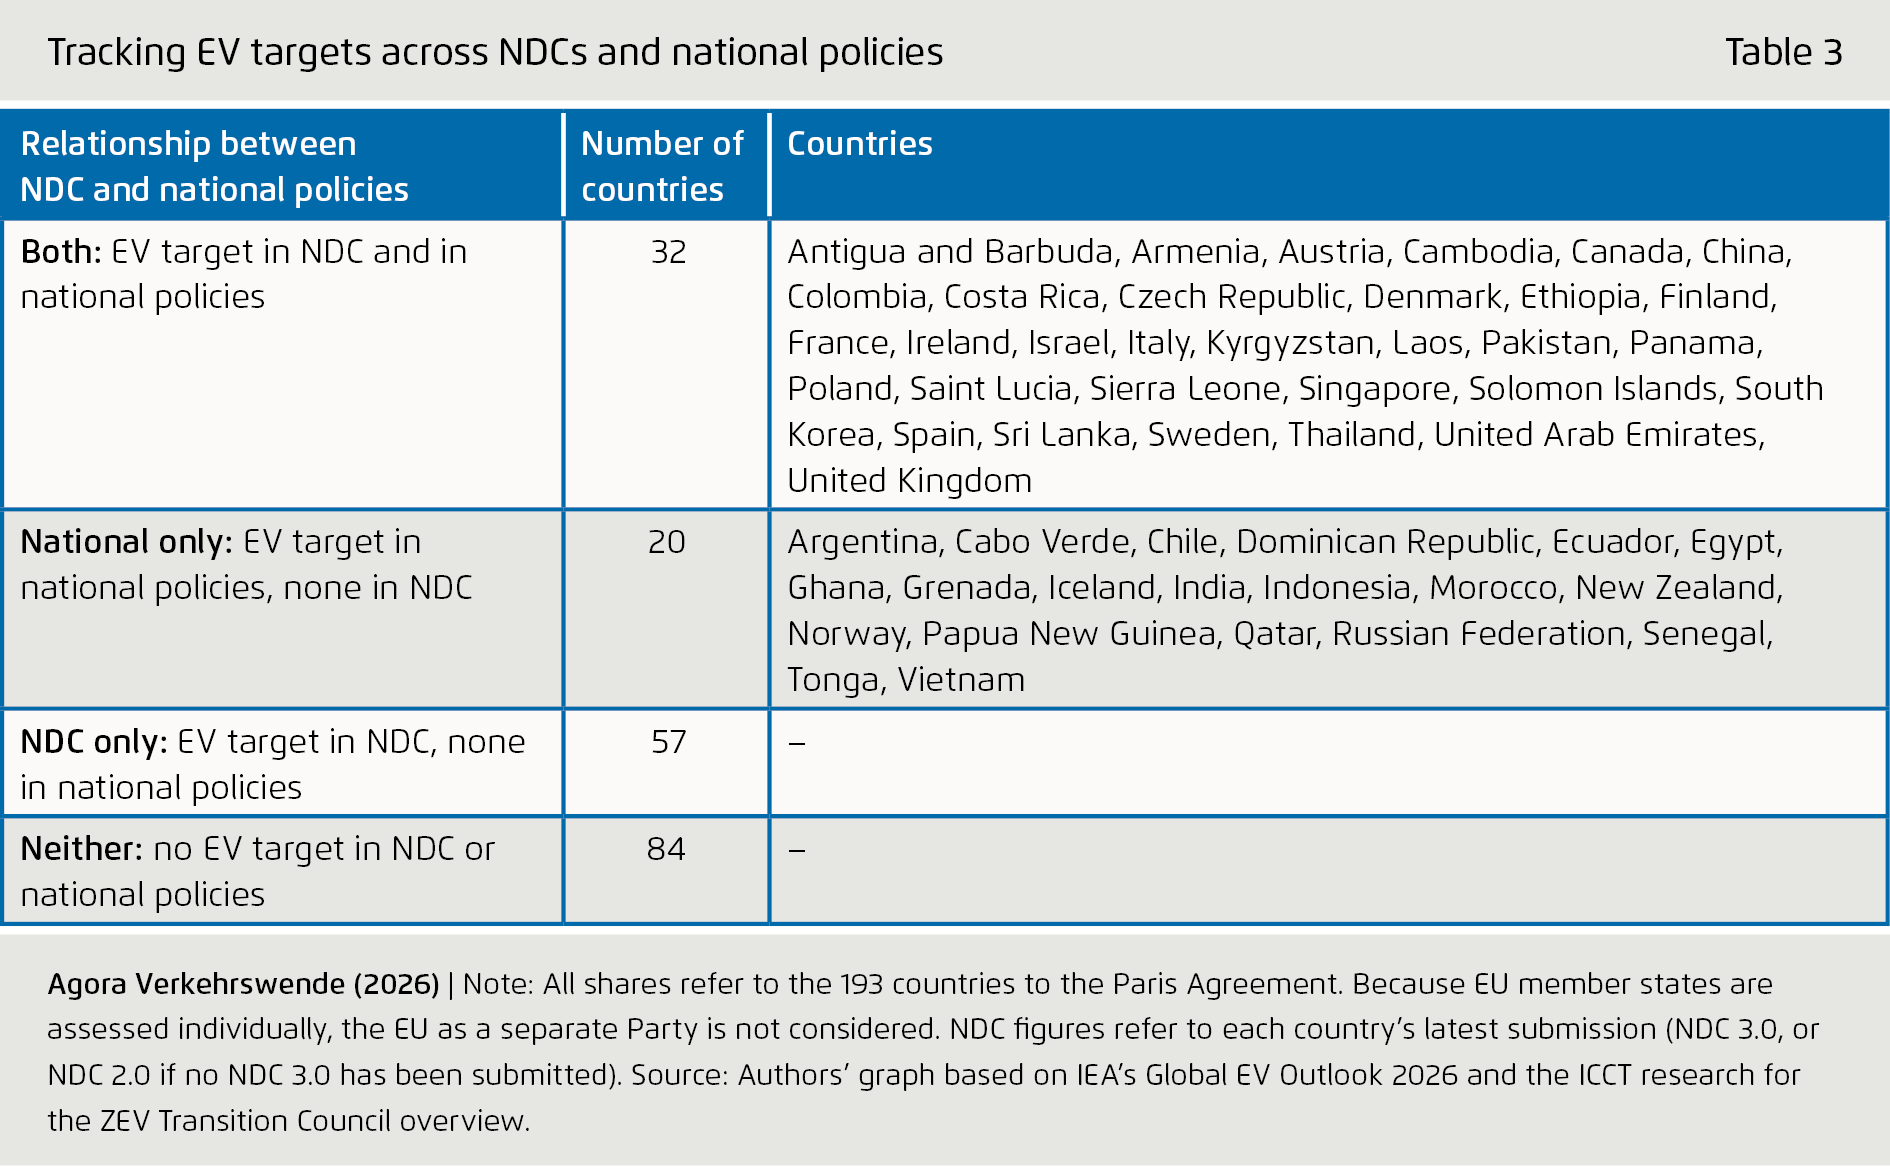
Across the 193 parties to the Paris Agreement, 52 (27 percent) have established valid national policy documents containing explicit EV targets. Unlike the previous sections, which assess NDC rounds separately, this section considers a country's currently active NDC submission (i.e. its NDC 3.0, or its NDC 2.0 where an NDC 3.0 has not yet been submitted). On this basis, 89 countries (46 percent) include an EV target in their NDC, and 109 countries (56 percent) have committed to an EV target either in their NDC or within national policies. Together, these 109 countries represent 77 percent of global car sales,3 encompassing major automotive markets such as China and the United Kingdom (covered under both frameworks), Germany (covered via its NDC) and India (which holds national EV targets despite having none in its NDC).
However, as shown in the table below, there is a notable disconnect between domestic planning and international reporting: 20 countries have adopted national EV targets without reflecting them in their NDCs, while 57 countries have communicated EV targets in their NDCs that could not be traced to corresponding primary domestic policy documents.
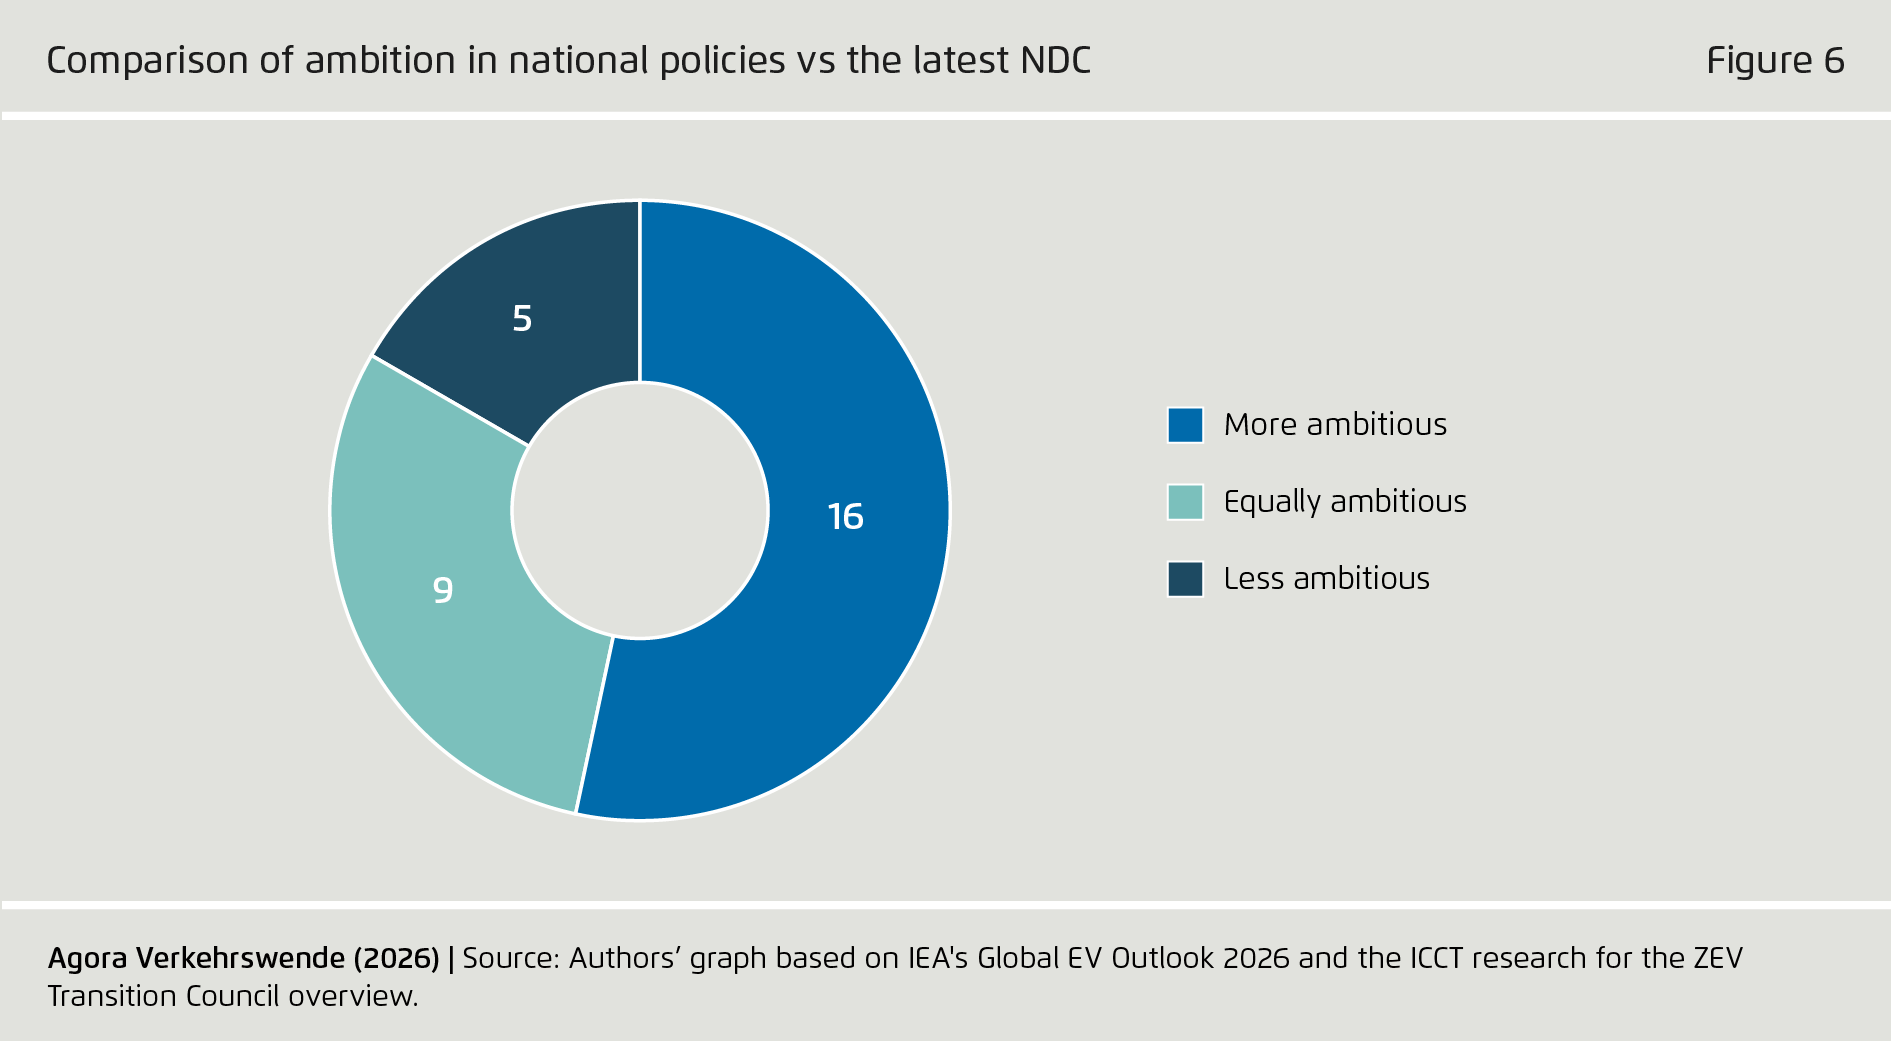
Among the 32 countries that include EV targets in both frameworks, international NDC pledges frequently lag behind domestic policy ambition. Because a single national policy or NDC often defines separate targets for multiple vehicle categories, comparing ambition requires looking at matching vehicle segments (LDVs, buses, HDVs or 2/3 wheelers) and matching metrics (i.e. new sales shares, total fleet stock, etc.). This was possible for 31 segment pairs across 22 countries. Within this comparable group, nearly half of the national targets (16 cases) are more ambitious than the country’s NDC (either through an earlier target year, a higher electrification rate, or both). In nine cases the national policy and NDC target are fully aligned, and in only five cases the NDC pledge exceeds existing domestic policy documents. This indicates clear potential for governments to strengthen their international transport commitments simply by aligning their NDCs with existing national targets.
5.2 Scope of national EV targets
National EV policies vary considerably in their sectoral coverage and legal weight. Because a single policy document often sets distinct goals for multiple vehicle categories, the 52 countries with national policies account for 98 segment-specific targets in total (alongside three countries that do not specify a segment). Similarly to what found in the NDCs, light-duty vehicles (LDVs, including passenger cars and public fleets) are by far the most covered segment, with 46 countries including a target in this segment, followed by buses (26 countries), heavy-duty vehicles (15 countries) and two- and three-wheelers (11 countries,).
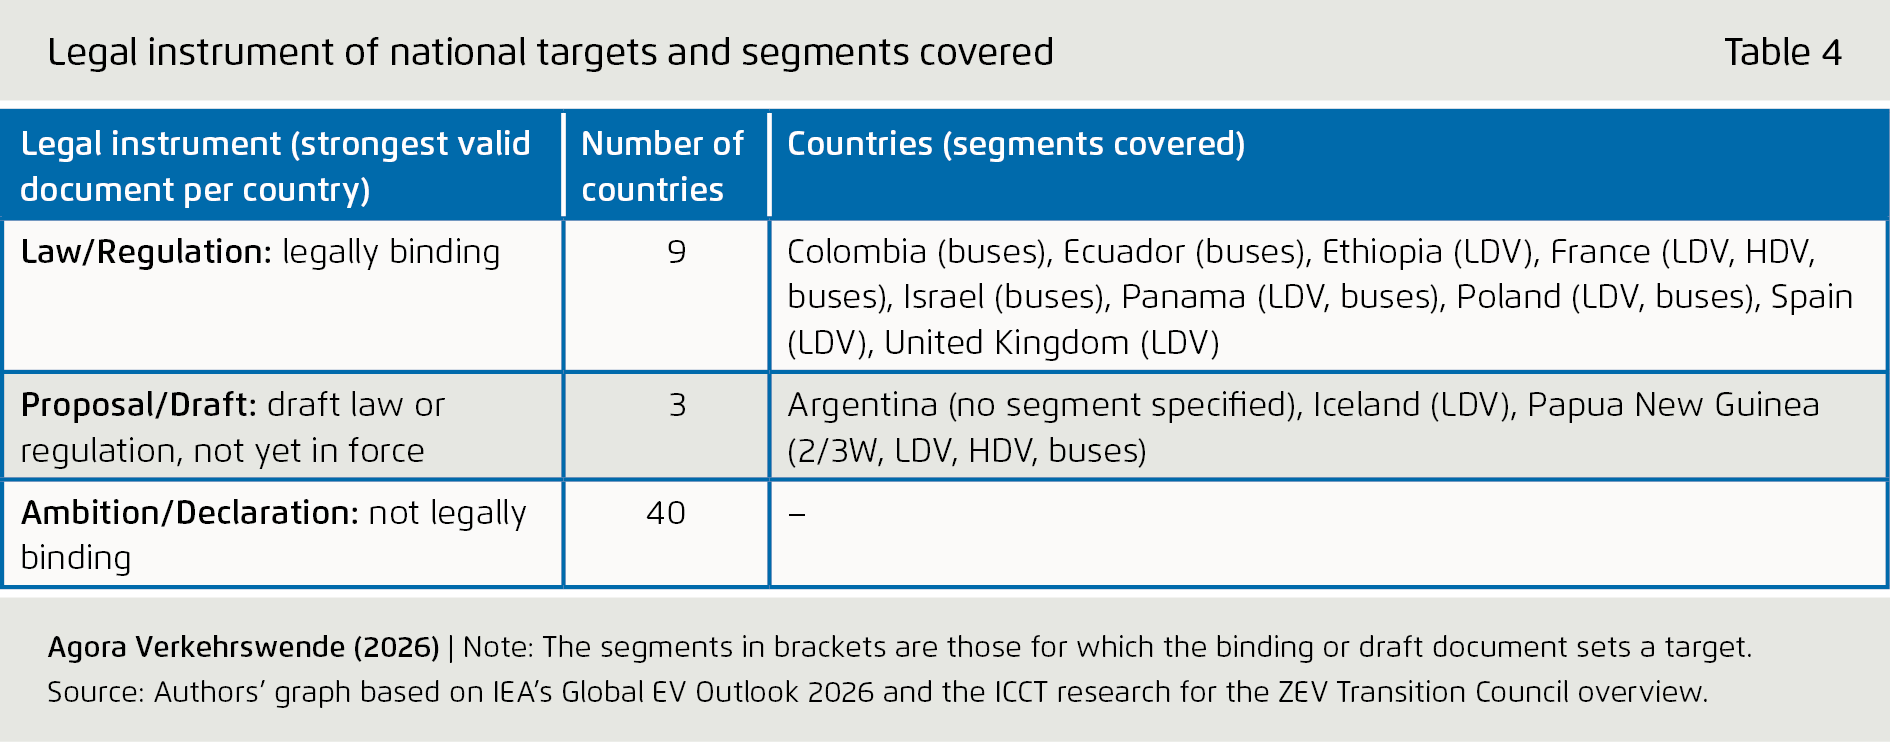
Unlike NDCs, domestic targets can be enforced by legislation. However, classifying each country by its strongest valid policy instrument — binding law or regulation, legislative draft, or non-binding declaration — reveals that most national targets remain aspirational. Of the 52 countries, nine (17 percent) have enacted legally binding laws or regulations. The remaining 43 countries rely on instruments that are not (yet) legally binding; in most cases (40 countries) these take the form of political declarations or roadmaps. Moreover, legal enforceability rarely extends across the entire transport sector: as shown in Table 2, binding legislation is concentrated mostly in LDVs.
6. Methodological notes
Data sources and selection criteria: The analysis builds on the IEA's Global EV Outlook 2026 and the ICCT research for the ZEV Transition Council overview, supplemented by targeted primary research. Only primary government sources, such as laws, regulations, draft legislation, official roadmaps and declarations of intent, were considered valid; secondary sources such as press releases or media interviews were excluded. All database entries were cross-checked against original source documents. Targets with a horizon prior to 2025, broken URLs, goals superseded by newer policies or figures that could not be verified in the cited primary document were excluded.
Classification of legal instruments: Countries are categorised by their strongest legal instrument, though borderline cases exist. For example, Israel’s government decision is classified under Law/Regulation (legally binding) as it carries direct executive obligation, making it stronger than a strategy document even if weaker than a parliamentary statute. Legislative Proposals/Drafts (Argentina, Iceland, Papua New Guinea) represent formal steps toward regulation but are counted as non-binding until enacted into law. National strategies and action plans without statutory backing are grouped under Ambition/Declaration.
Assessing comparative ambition: Comparisons are restricted to countries where an EV target exists for both the national policy and the country’s latest NDC for the matching vehicle segment. Ambition is evaluated along two dimensions: the target year and the electrification level (e.g., 80 percent or 100 percent of new sales). Phase-out bans on internal combustion engine vehicles are treated as a 100 percent zero-emission share of new sales. A national target is classified as more ambitious if its target year is earlier or the same and its electrification level is higher or the same (with at least one parameter strictly stronger), equally ambitious if both parameters match, and less ambitious if at least one parameter is weaker without the other compensating.
7. Final remarks
This analysis of the third-generation NDCs and national EV policies provides a global snapshot of political intent for the electric vehicle transition at a critical juncture. The findings reveal a world standing at the crossroads: while formal ambition is rising, commitments often lack the specificity required to transform pledges into economic reality.
For industry leaders, these findings paint a mixed picture. On one hand, the upward trajectory in EV ambition, coupled with the fact that over 77 percent of the global car market is already covered by NDC-based or national policy transport electrification or ICE phase-out targets, demonstrates a clear direction of travel for markets and associated regulatory frameworks. The transition to net zero is not a hypothetical future; it is the established policy trajectory of the world’s largest economies and a growing number of emerging markets.
On the other hand, a persistent lack of specificity, particularly with a view to charging infrastructure, coupled with wavering or withdrawn targets by some nations, is creating uncertainty that can delay investment and slow the pace of change. Domestic ambition frequently outpaces what governments report to the UNFCCC: 20 countries have established national EV targets without including any EV goal in their active NDC, and among countries with directly comparable targets in both frameworks, nearly half have set more ambitious goals at the national level than in their NDC. Aligning future NDC submissions with existing national transport strategies thus represents an immediate, low-hanging fruit for increasing international climate ambition.
Similarly, international pledges must be anchored in credible domestic execution. Currently, 57 countries communicate an EV target in their active NDC without a corresponding primary national policy document, and among the 52 countries that do have national EV policies, 83 percent rely solely on non-binding strategies or political declarations. Because NDC targets are not legally binding domestically, translating both NDC pledges and national roadmaps into enforceable domestic legislation is essential to provide long-term regulatory certainty. Industries cannot plan confidently on aspirations alone; they require the clarity of detailed roadmaps, stable regulations and synchronised infrastructure rollouts.
The path forward requires converting political ambition into market certainty, so that market participants have reliable conditions for engaging in long-term planning. The imperative for the next NDC cycle and parallel national policymaking is therefore clear:
1. Countries should bridge the implementation gap. This means upgrading the prevalent Tier 2 policies into Tier 1 action plans by attaching specific, annualised and funded targets for vehicle sales, public fleet renewal and the deployment of public and private charging infrastructure.
2. High-profile political pledges, such as the ZEV Declaration, must be locked into formal NDC commitments to provide the stable, long-term regulatory certainty that industries require to invest at scale.
3. This planning should be supported by mobilising tailored finance. Ambitious targets in emerging economies will remain aspirational without dedicated capital. This requires designing bankable EV and infrastructure projects that can attract international climate finance and development bank funding.
4. Wealthier nations should back their domestic strategies with clear public financing mechanisms to de-risk private investment, particularly for grid upgrades and charging access.
5. Moving beyond isolated vehicle adoption targets is essential. The transition's success hinges on the resilience of the entire industrial ecosystem. This requires governments to conduct structured national assessments and develop integrated plans that address all steps of the EV lifecycle.
To support the realisation of an industrial EV ecosystem, Agora Verkehrswende has developed a framework for analysing the comprehensiveness of EV policy instruments (see next figure). This tool is designed to reveal potential blind spots and gaps across the EV ecosystem, thus serving as a starting point for delineating necessary action areas.
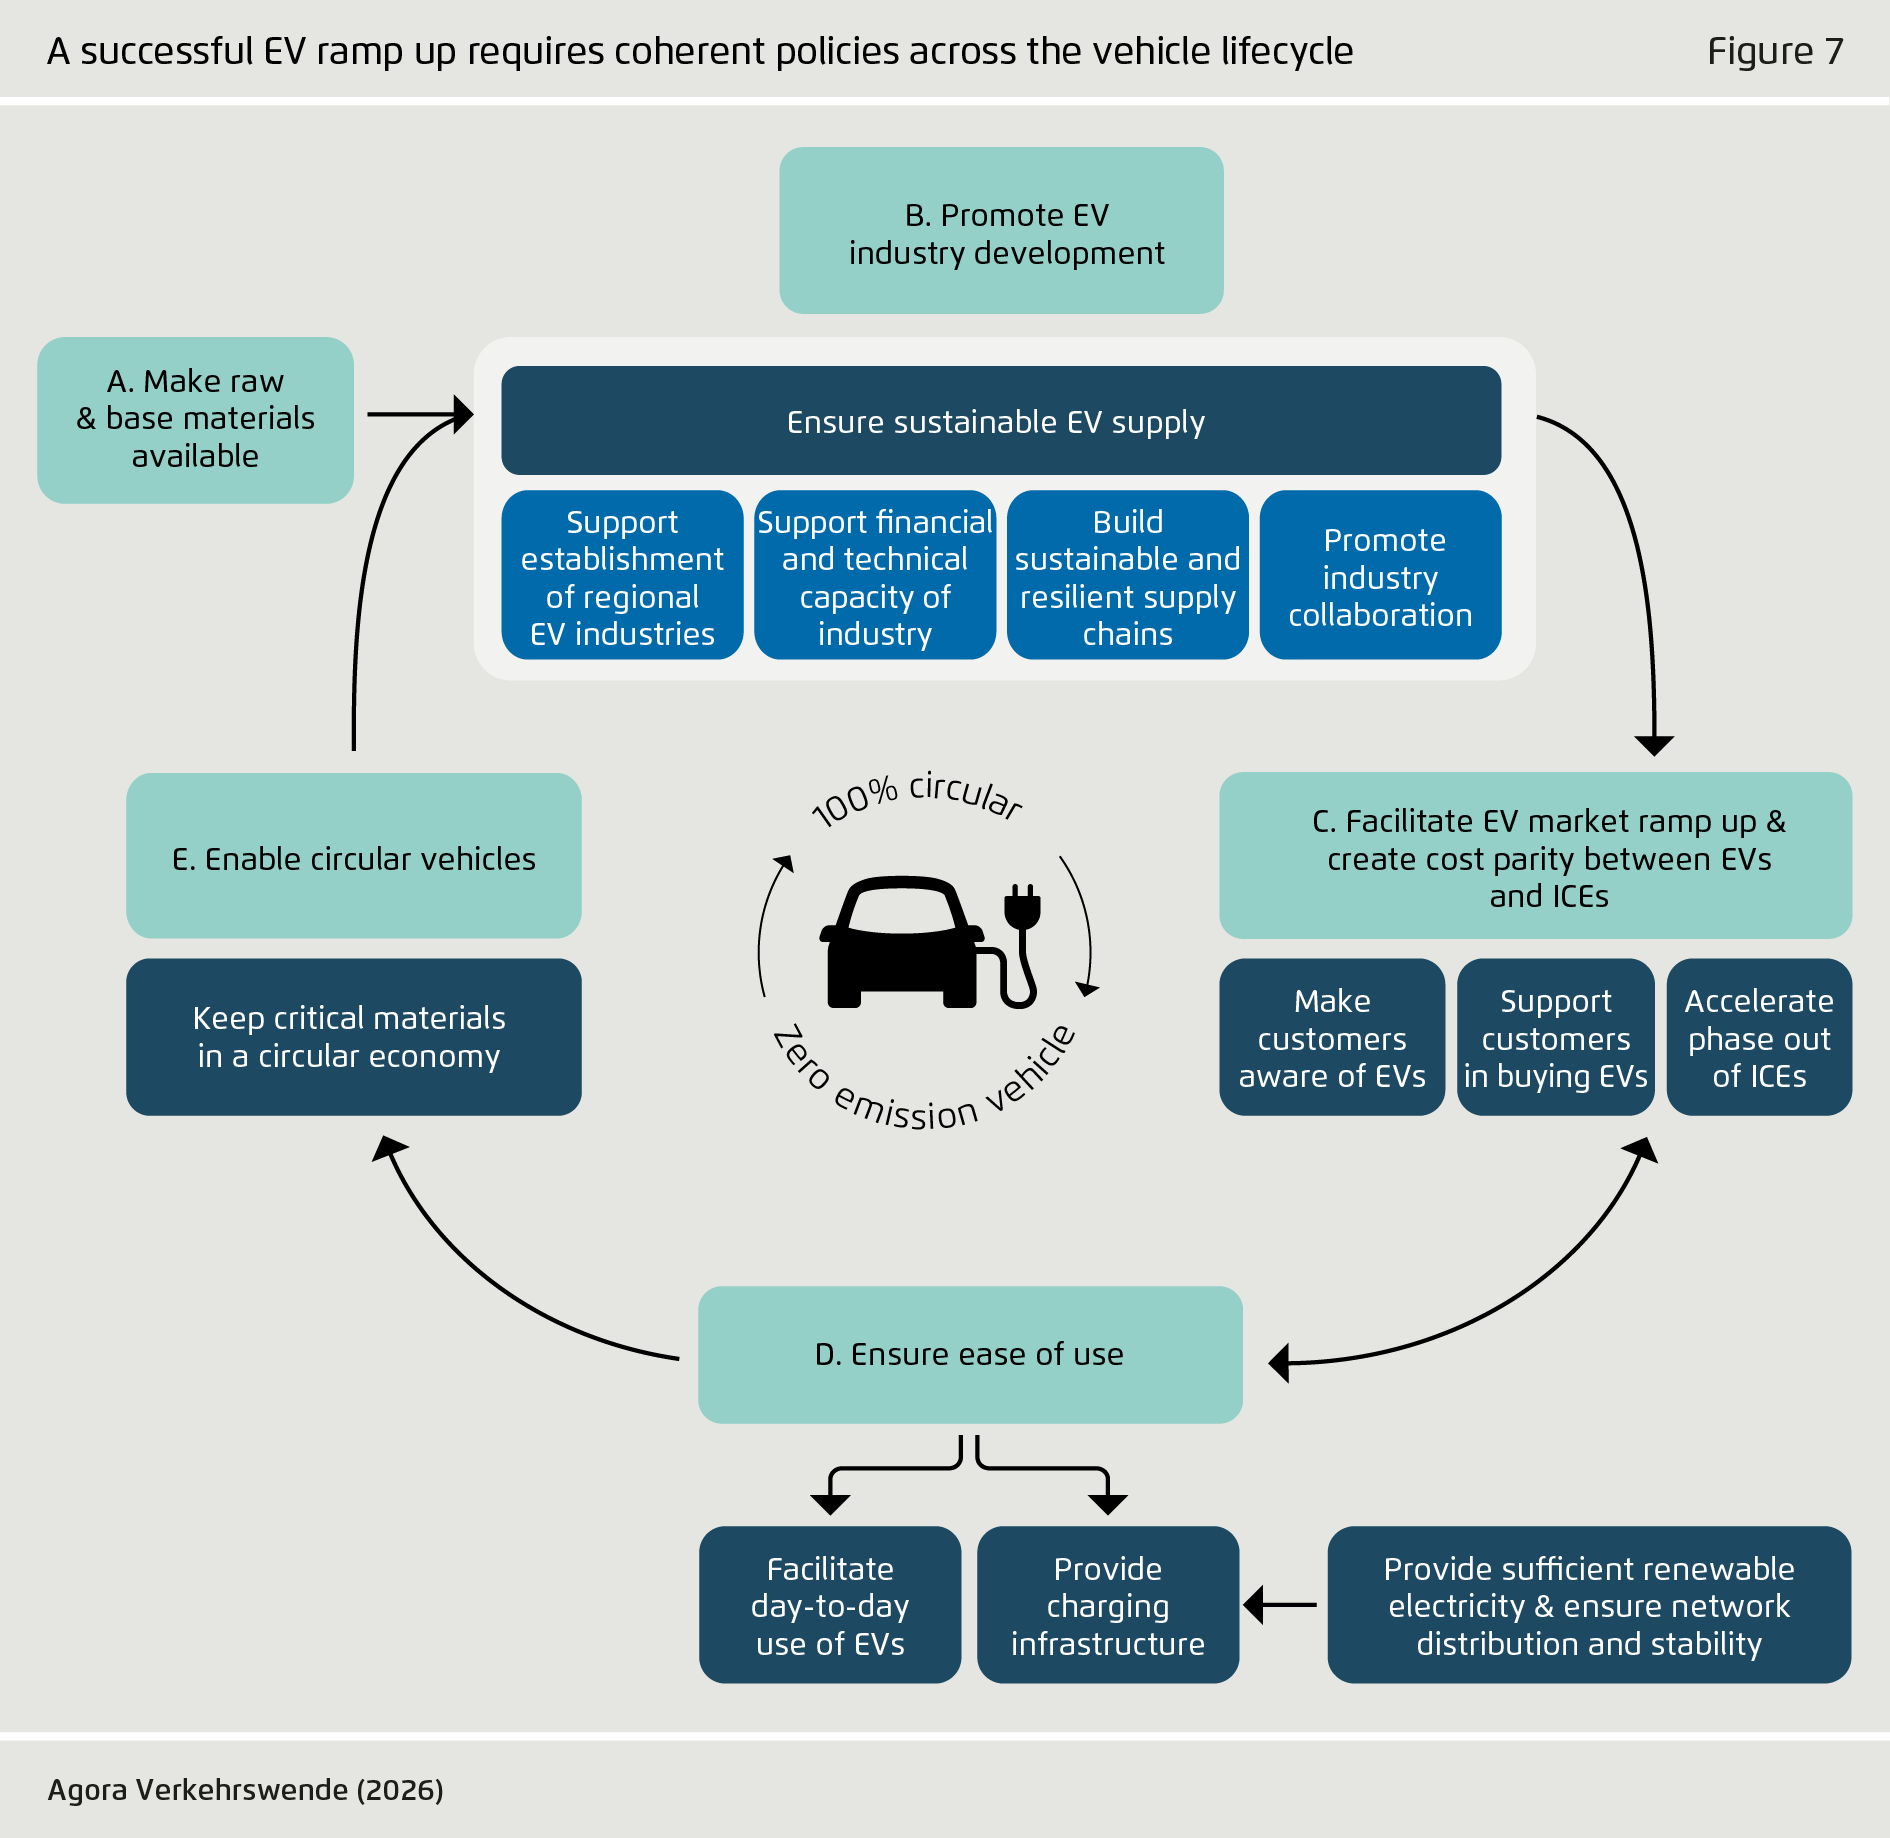
The framework covers five critical areas: (A) securing sustainable raw material supply; (B) fostering competitive regional industries and supply chains; (C) creating effective market push-pull dynamics to achieve cost parity; (D) guaranteeing ease of use through robust infrastructure and renewable energy integration; and (E) enabling circularity for vehicles and batteries from the outset. Integrating these areas into national planning can help ensure the EV transition not only drives emission reductions, but also promotes economic growth, job creation and energy security.
1 Based on 2023 market figures for 57 countries obtained from The Global Economy.
2 Republic of Uganda Sciences, Technology & Innovation Secretariat of the President (2023). National E-Mobility Strategy.
3 Based on 2023 market figures for 57 countries obtained from The Global Economy.